What Does Hemförsäkring Actually Cover in Sweden?
Navigating the world of Swedish administrative requirements can feel like walking through a dense forest, especially when it comes to something as crucial yet opaque as insurance. You've just landed, maybe you've managed to sort out your apartment, and suddenly everyone starts asking if you have "hemförsäkring." But what on earth is it, really? This guide will cut through the fog, explaining exactly what a standard Swedish home insurance policy covers, why it's so vital for every resident, and what you need to know to protect yourself and your belongings.
Understanding the Basics of Swedish Home Insurance (Hemförsäkring)
When you first hear "home insurance," you might picture a policy that protects the physical structure of a house. In Sweden, especially if you're renting, hemförsäkring is a beast of a different color. It’s far more comprehensive than just coverage for bricks and mortar, acting as a broad safety net for your personal life. This is often a huge point of confusion for newcomers who are used to more segmented insurance systems back home. You're probably thinking, "I'm just renting, why do I need to insure the home?" And that's exactly where the nuance lies.
More Than Just Your "Home" – It's a Lifesaver
For most expats living in a rented apartment, whether it's a first-hand contract or a second-hand rental secured through platforms like Blocket or even Spotahome, hemförsäkring isn't primarily about the building itself. The building's owner (the landlord or the bostadsrättsförening if you own a co-op apartment) is responsible for insuring the physical structure. Your hemförsäkring is essentially a personal all-in-one insurance package designed to protect you and your stuff, and, crucially, cover you for certain liabilities that could otherwise lead to financial ruin. Ignoring it is really playing with fire, metaphorically speaking, because without it, you're entirely exposed to a myriad of risks that are simply part of everyday life. There are countless accounts of people regretting not getting it, from a burst pipe in their rented apartment to a stolen bicycle, or even causing accidental damage to a neighbour's property.
Key Components of a Standard Hemförsäkring Policy
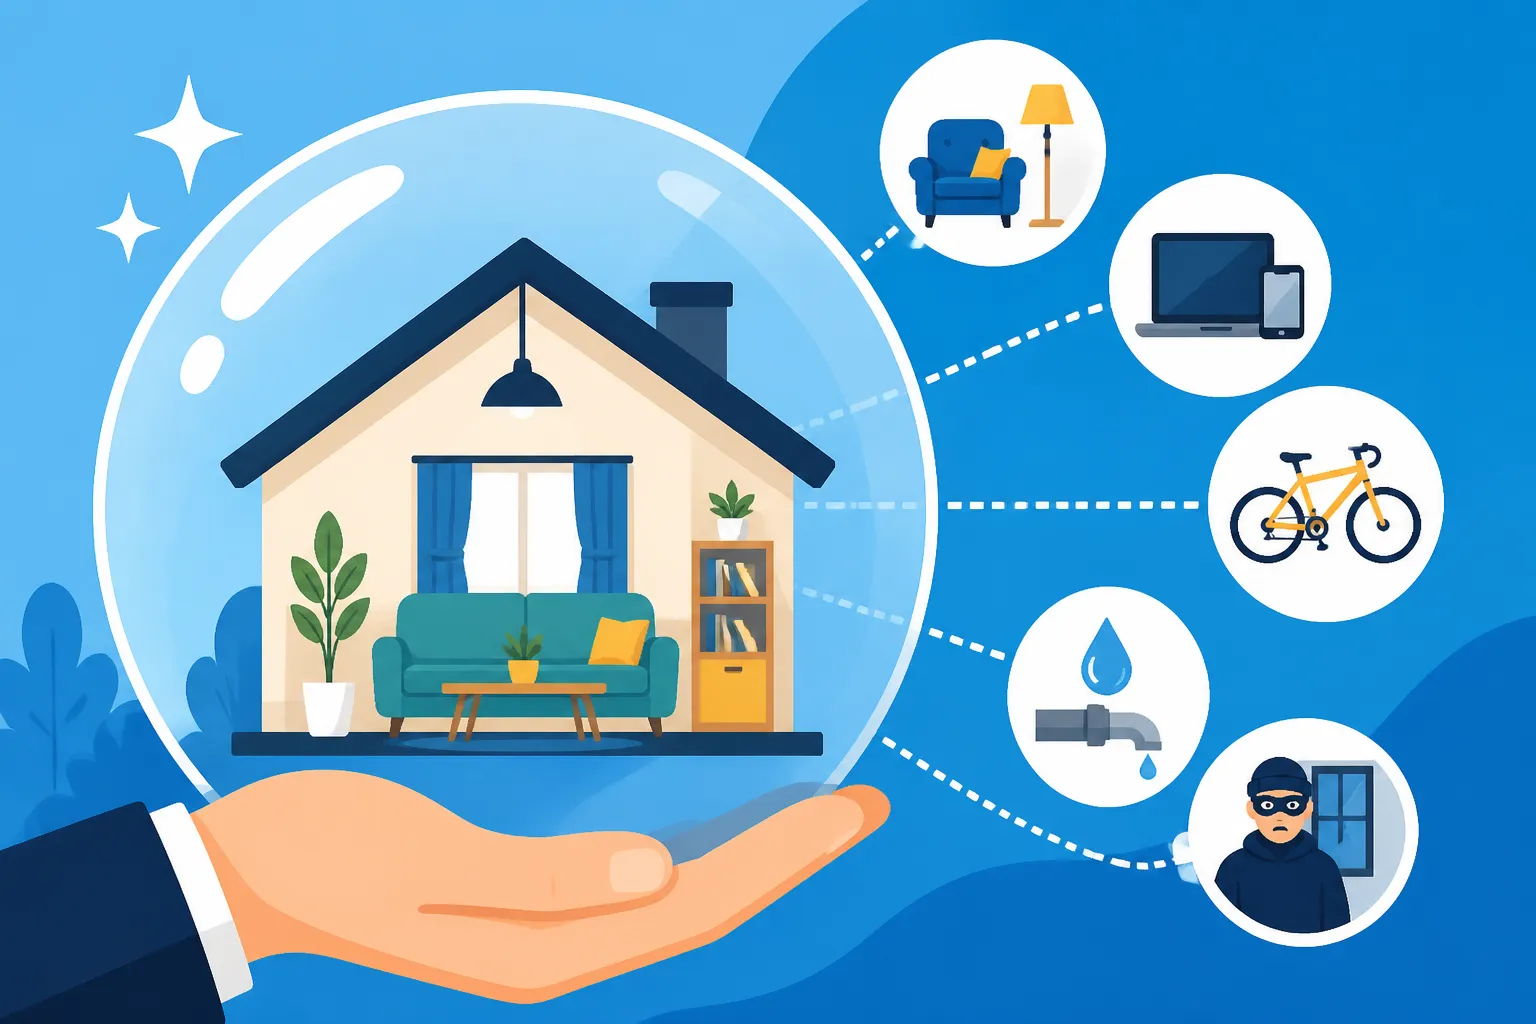
A standard hemförsäkring policy in Sweden is actually a bundle of several different types of insurance. It's designed to give you peace of mind across various aspects of your life, not just within the four walls of your apartment. Let's break down the main components you'll typically find:
- Property Protection (Lösöre): This is what covers all your personal belongings inside your home. Think furniture, electronics, clothing, books, kitchenware – essentially anything that would fall out if you tipped your apartment upside down. It protects against common perils like fire, theft, and water damage.
- Liability Protection (Ansvarsskydd): This is an absolutely critical part, especially for renters. It covers you if you accidentally cause damage to someone else's property or injure someone, and you are held legally responsible. Imagine the horror of accidentally flooding your downstairs neighbour's apartment – this is what kicks in.
- Legal Aid (Rättsskydd): Should you become involved in certain legal disputes, this component helps cover your legal costs, such as lawyer fees. It’s not for every kind of legal battle, but it can be a lifesaver in specific situations.
- Travel Insurance (Reseskydd): Surprisingly, your hemförsäkring often includes basic travel insurance for short trips abroad. This typically covers emergency medical expenses, lost luggage, and sometimes even delays, usually for up to 45 consecutive days.
- Assault Protection (Överfallsskydd): This offers financial compensation if you are a victim of assault, regardless of whether the perpetrator is identified or prosecuted. It’s a somber but important inclusion in the safety net.
As you can see, it's a far-reaching policy that goes well beyond just the physical structure of your home. It’s fundamental to settling in and feeling secure in Sweden, almost as important as getting your Personnummer: The Gateway to Swedish Healthcare or setting up your Opening a Bank Account in Sweden: A Step-by-Step Guide.
Delving Deeper into Specific Coverage Areas
Understanding the broad categories is one thing, but knowing the nitty-gritty of what’s actually covered can make all the difference when something unexpected happens. This is where many expats get tripped up, often assuming coverage they don't have, or overlooking vital add-ons.
Property Protection: What Your Belongings Are Worth
The Lösöre part of your hemförsäkring is your personal bodyguard for all the items you own and bring into your home. This includes everything from your expensive laptop and television to your cherished books, clothes, and even the food in your fridge. The coverage amount is typically set when you purchase the policy, so it's essential to estimate the value of your possessions accurately. If you underestimate, you risk underinsurance, meaning the payout won't be enough to replace everything if a major incident occurs.
Let's say a fire breaks out in your building – a terrifying thought, but it happens. Your hemförsäkring would cover the cost of replacing your furniture, electronics, and personal items, up to the sum insured. If your apartment is broken into and your valuables are stolen, a police report (polisanmälan) is key, and your insurance would then compensate you for the loss. Water damage, perhaps from a leaky pipe or a washing machine malfunction, is another common claim. The policy would typically cover the damage to your movable property and also potentially the cost of temporary accommodation if your home becomes uninhabitable.
However, standard property protection doesn't always cover accidental damage that you cause yourself. Dropping your new smartphone, spilling coffee on your laptop, or accidentally knocking over an expensive vase? That's usually where an Allriskförsäkring or Drulleförsäkring (sometimes called "clumsiness insurance" in a direct translation) comes into play. This is an add-on, and honestly, for anyone prone to a bit of clumsiness or just wanting extra peace of mind for those "oops" moments, it's highly recommended. It covers sudden, unforeseen external events that damage your property.
Liability Protection: When You Accidentally Cause Damage
This is arguably one of the most crucial elements of hemförsäkring, especially for those Renting a Home in Sweden: How the First- and Second-Hand System Works. The Ansvarsskydd protects you from significant financial claims if you are held liable for causing damage or injury to a third party.
Consider these scenarios:
- You forget to turn off the tap, leading to an overflow that floods not only your bathroom but also seeps into the apartment below, ruining their ceiling and furniture. Without liability protection, you could be on the hook for tens or even hundreds of thousands of SEK in repair costs and compensation.
- Your child accidentally breaks an expensive antique while visiting a friend's home.
- You're cycling and accidentally collide with a pedestrian, causing them injury and damaging their property.
In all these cases, if you're deemed responsible, your liability protection would cover the costs, up to a certain limit (often several million SEK). Landlords almost universally require tenants to have hemförsäkring precisely because of this liability component. They want assurance that if you inadvertently damage their property, there's an insurance company to foot the bill, not you directly. It's a huge weight off your shoulders, knowing that one silly mistake won't bankrupt you.
Legal Aid and Identity Theft Protection
The Rättsskydd component is there to cover legal costs in certain disputes. Let’s say you have a disagreement with a contractor who performed shoddy work on your bostadsrätt (co-op apartment) or a complex dispute arises with a previous landlord after moving out, related to your Tenant Rights in Sweden: Contracts, Rent, and the Hyresnämnden and your deposit. If the matter escalates and requires legal representation, your insurance can cover a significant portion of your lawyer's fees and other court costs, minus your deductible. There are usually strict conditions on what types of disputes are covered and limits on the amount, so it's not a blanket "free lawyer" card, but it's a valuable safety net.
Identity theft is an unfortunate reality in our increasingly digital world, and it can be a nightmare to unravel. Some hemförsäkring policies now include identity theft protection, which provides expert assistance to help you clear your name, contact relevant authorities, and restore your financial identity if you become a victim. This can involve covering legal fees, administrative costs, and expert consultation to navigate the complex process of proving your innocence and securing your personal data. Given how much of life in Sweden revolves around your personal identification, like getting your Getting a Swedish ID Card After Your Personnummer, this can be a very welcome protection.
Essential Add-ons and What's NOT Covered
While a standard hemförsäkring is extensive, it's not a one-size-fits-all solution. There are key differentiators based on whether you rent or own, and important optional add-ons that many people find invaluable. Just as crucial is understanding what your policy explicitly doesn't cover, to avoid any nasty surprises.
Enhancing Your Hemförsäkring: Common Supplements
As we touched upon, the Allriskförsäkring or Drulleförsäkring is probably the most popular add-on. It's for those everyday mishaps – the coffee on the laptop, the phone dropped in the toilet, or the glass that slips from your hand. Without it, you'd be out of pocket for these "oops" moments. It's a relatively small extra cost for a lot of added peace of mind.
Another important supplement is in the area of travel insurance (Reseförsäkring). While a basic travel component is usually included in your hemförsäkring, this coverage is often limited. It typically covers trips up to 45 days, for emergency medical care and lost luggage up to a certain value. If you travel frequently, for longer periods, or engage in high-risk activities, you’ll likely need separate, comprehensive travel insurance. This also means if your primary method of staying connected while abroad is via an eSIM, you'd make sure that your phone itself is covered by the hemförsäkring's general contents protection, and for reliable global connectivity when you're exploring beyond Sweden's borders, you might look into a service like Airalo.
For homeowners, the insurance landscape shifts significantly. If you own a bostadsrätt (a co-op apartment), you'll need an utökad bostadsrättsförsäkring (extended co-op apartment insurance). This is a vital add-on that covers the fixed interior fittings of your apartment that you are responsible for, such as kitchen cupboards, flooring, wallpaper, and fixtures. Your bostadsrättsförening (BRF) will have a policy for the building's shell, but not your specific interior. Without this, if your pipes burst and damage your brand new kitchen, your hemförsäkring would cover your movable items, but not the actual kitchen fixtures. This is a crucial distinction when you're looking into Understanding Bostadsrätt: Buying into a Swedish Housing Co-op.
If you own a villa (a freestanding house), you'll need a villahemförsäkring, which is essentially a hemförsäkring combined with villaförsäkring (house insurance). This covers the physical structure of your house, outbuildings, and the plot of land itself, in addition to all your personal belongings and the other standard hemförsäkring components. This is a much bigger policy, reflecting the significantly greater responsibilities of owning a detached property. It's a key consideration if you're looking into Buying Property in Sweden as a Foreigner: A Complete Guide.
Common Exclusions and Important Caveats
It’s just as important to understand what your hemförsäkring won't cover. No insurance policy covers everything, and knowing the limitations can save you a lot of heartache (and money).
- Wear and Tear / Gradual Damage: Your policy won't cover things that break down due to age, normal use, or gradual deterioration. For instance, an old fridge that simply stops working isn't an insurance claim.
- Intentional Damage / Neglect: If you intentionally damage your property, or if damage occurs because of gross negligence (e.g., leaving a window wide open during a storm and your apartment gets flooded), your claim will likely be denied.
- Specific High-Value Items: Jewellery, art, expensive watches, or unique collections often have specific limits on their coverage under standard property protection. If you have particularly valuable items, you might need to declare them separately and potentially pay an additional premium for a specific värdeföremålsförsäkring (valuable items insurance).
- Pest Infestations: While some policies might offer basic coverage for certain pests, extensive infestations often fall outside the scope of standard hemförsäkring.
- Unapproved Subletting: If you're Finding a Second-Hand Rental (Andrahand) in Sweden Safely and decide to sublet your apartment without proper approval from your landlord or BRF, any damage that occurs during that period might not be covered, as you could be in breach of contract.
- High Deductible (Självrisk): Remember, almost all claims will involve a deductible, which is the fixed amount you pay out-of-pocket before the insurance company covers the rest. This amount can vary, and choosing a higher deductible often lowers your monthly premium, but means you pay more per claim.
Always read the full terms and conditions (försäkringsvillkor) of your policy. It might be tedious, especially if it's in Swedish, but it’s your ultimate reference point for what is and isn't covered. If in doubt, call your insurance provider and ask for clarification, ideally with an interpreter if your Swedish isn't yet fluent.
Choosing the Right Policy and Practical Advice
Selecting the right hemförsäkring can seem daunting with so many providers and options. It’s not just about finding the cheapest premium; it’s about getting coverage that genuinely suits your specific situation in Sweden.
Factors to Consider When Selecting Your Hemförsäkring
Your housing situation is the primary factor. Are you in a hyresrätt (rental apartment), a bostadsrätt (co-op apartment), or a villa (freestanding house)? This will fundamentally determine the type and extent of property coverage you need. For renters, the primary focus is your personal belongings and liability. For bostadsrätt owners, it's those interior fittings. For villa owners, it’s the whole structural kit and caboodle.
Next, consider the total value of your belongings. Take an inventory, even a rough one, to estimate how much it would cost to replace everything you own. This helps you choose an appropriate sum insured for your lösöre. Don’t forget to factor in items you might accumulate as you settle in.
Your lifestyle also plays a role. Do you travel frequently? If so, you might want to review the travel insurance component and consider if separate, more comprehensive travel insurance is necessary. Do you own expensive gadgets, jewellery, or sports equipment? These might require specific riders or a higher sum insured.
Finally, it's time to compare providers. Sweden has several large and reputable insurance companies, including Folksam, If Skadeförsäkring, Länsförsäkringar, and Trygg-Hansa. Each offers slightly different packages, terms, and customer service experiences. Many provide online quotes, and some have English-speaking support or information. Don't be afraid to get quotes from a few different companies. Look beyond just the price tag; examine the deductibles, the specific coverage limits for different types of items, and any optional add-ons that might be important to you. Many insurers also offer discounts if you combine different policies (e.g., home and car insurance). This due diligence for Setting Up Your Home in Sweden: Utilities, Internet, and Insurance is time well spent.
Making a Claim and What to Expect
Should the worst happen and you need to make a claim, here’s a general rundown of what to expect:
- Contact Your Insurer Immediately: As soon as possible after the incident (theft, fire, water damage), contact your insurance company. Many have dedicated phone lines or online portals for claims. The sooner, the better.
- Report to the Police (if applicable): For theft, vandalism, or assault, you must file a police report (polisanmälan). Your insurance company will require the police report number.
- Document Everything: Take photos or videos of any damage. Make a list of all damaged or stolen items. Gather receipts, bank statements, or any proof of ownership and value you have for these items. The more evidence you have, the smoother the process will be.
- Minimise Further Damage: Take reasonable steps to prevent further damage. For instance, if you have a water leak, try to stop the source if it's safe to do so.
- Be Prepared for Questions: The insurance company will ask for detailed information about what happened, when, and where. Be honest and thorough.
- Understand the Deductible: Remember that you will pay the självrisk (deductible) amount yourself, and the insurance company will cover the rest up to your policy limits.
- Processing Time: Claims can take time to process, especially if they are complex or require investigations. Patience is key. Stay in regular contact with your insurer for updates.
The process can be frustrating, especially if you're dealing with it in a foreign language while already under stress. Don't hesitate to ask for clarity if you don't understand something. Many insurers have customer service agents who can speak English, or you can ask a Swedish-speaking friend to help you navigate the call.
Here's a quick overview of Hemförsäkring types and their typical coverage:
| Feature/Coverage | Hyresrätt (Rental Apartment) | Bostadsrätt (Co-op Apartment) | Villa (Detached House) |
|---|---|---|---|
| Primary Focus | Personal belongings & Liability | Personal belongings & Liability + Interior | Building structure, belongings & Liability |
| Lösöre (Contents) | Yes | Yes | Yes |
| Ansvarsskydd (Liability) | Yes | Yes | Yes |
| Rättsskydd (Legal Aid) | Yes | Yes | Yes |
| Reseskydd (Travel) | Basic (e.g., 45 days) | Basic (e.g., 45 days) | Basic (e.g., 45 days) |
| Överfallsskydd (Assault) | Yes | Yes | Yes |
| Building Structure | No (landlord's responsibility) | No (BRF's responsibility) | Yes |
| Fixed Interior Fittings | No (landlord's responsibility) | Yes (with Utökad Bostadsrättsförsäkring) | Yes (as part of building) |
| Common Add-ons | Allriskförsäkring | Allriskförsäkring | Allriskförsäkring, Extended Travel |
This table highlights why understanding your housing type is the first step to securing adequate protection. While it might seem like a lot to take in, having hemförsäkring is one of those non-negotiables for a smooth and secure life in Sweden. It's truly a shield that protects your wallet and your peace of mind from life's unexpected curveballs.
Disclaimer
Please note that this guide provides general information about hemförsäkring in Sweden and should not be considered legal or financial advice. Insurance policies and terms can vary significantly between providers and are subject to change. It is crucial to always read the specific terms and conditions of any insurance policy you consider or purchase and to contact an insurance provider directly for personalised advice based on your individual circumstances.