Home Insurance (Hemförsäkring): Why It’s Essential in Sweden
Moving to a new country like Sweden, especially with all the excitement and challenges of settling in, often means that crucial administrative tasks like understanding insurance can get pushed to the back burner. Many newcomers, myself included, arrive thinking their existing home country insurance might cover them, or that a landlord's building insurance is enough. But trust me, overlooking hemförsäkring, or home insurance, in Sweden is a mistake you absolutely do not want to make. This guide will walk you through everything you need to know about why this seemingly simple policy is your ultimate safety net in your new Swedish life.
What Exactly is Hemförsäkring? Understanding Swedish Home Insurance
When you hear "home insurance" in your home country, you might immediately think of covering the physical structure of a house. In Sweden, hemförsäkring is a broader concept, and for most renters, it’s not about the building itself but about protecting you, your belongings, and your personal liability. It’s a vital piece of the puzzle that often gets misunderstood by expats, but once you grasp its scope, you'll see why it's truly indispensable.
More Than Just "Home" – It's Your Personal Safety Net
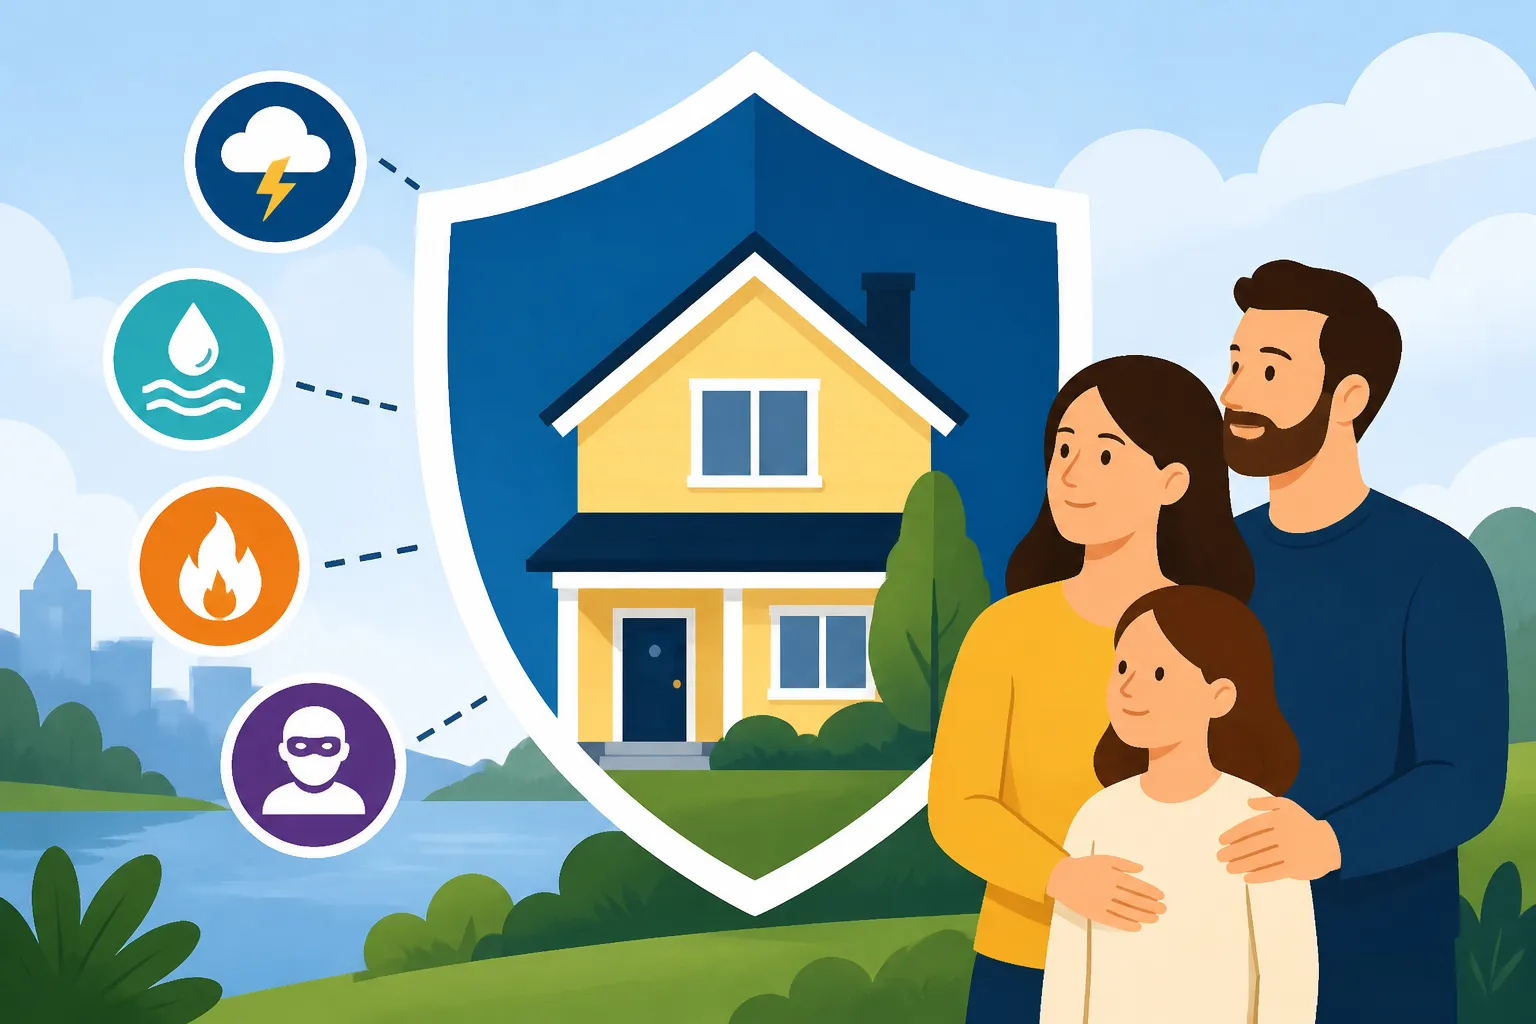
Let's clear up a common misconception right away. If you're renting an apartment in Sweden, your landlord almost certainly has insurance on the building itself. That covers the walls, the roof, the fixed installations – the physical structure. But what it doesn't cover is your personal belongings inside that apartment, nor does it cover you if you accidentally cause damage to the property or to a neighbor's property. This is where hemförsäkring steps in, acting as your personal fortress against a myriad of unforeseen circumstances.
Imagine you've just moved into your cozy new apartment in Stockholm, perhaps found through a platform like Spotahome, and you're still unpacking. Your landlord's insurance covers the building. But if a pipe bursts and ruins your brand-new furniture, your electronics, or even that precious antique rug you shipped from home, the landlord's insurance won't pay for your losses. It's your hemförsäkring that will protect the monetary value of your personal possessions. Without it, you'd be looking at a significant out-of-pocket expense to replace everything you own, which could easily run into tens or even hundreds of thousands of kronor. This is a common and often costly oversight for those new to the Swedish system.
Key Components of a Standard Hemförsäkring Policy
A standard hemförsäkring policy in Sweden is actually quite comprehensive, bundling several essential protections into one package. It's designed to cover various aspects of your life, not just within the four walls of your apartment, but even when you're out and about. Understanding these components will help you appreciate the value of this insurance.
Firstly, and perhaps most obviously, there's property protection (lösöre). This is what covers your personal belongings – everything from your clothes, furniture, and electronics to your kitchenware and books. The coverage limit, known as the försäkringsbelopp, is usually quite high, often between SEK 750,000 and SEK 1,500,000 for a standard apartment, but you can adjust it based on the value of your possessions. This means if your apartment is burgled, catches fire, or suffers water damage, your insurance company will help you replace your lost or damaged items, typically at their current market value, or even replacement value for newer items.
Secondly, and crucially for anyone renting, is liability protection (ansvarsskydd). This is a game-changer. If you, or someone in your household, accidentally cause damage to another person or their property, this part of the insurance covers the costs. For example, if your child accidentally breaks a neighbor's window, or if you cause a water leak that damages the apartment below yours, your liability insurance will cover the compensation claims. Without this, you could be facing enormous bills for damages, which can be devastating for anyone, let alone someone just starting out in a new country.
Then there's legal aid (rättsskydd). This component can cover the costs of legal assistance in certain types of disputes, such as if you need to go to court over a conflict that falls under your insurance terms. While it has limitations and typically involves a deductible and a maximum coverage amount, it can be a lifesaver if you find yourself in a sticky legal situation that is both unexpected and expensive.
A delightful surprise for many expats is the inclusion of travel insurance (reseskydd). Most standard hemförsäkring policies include basic travel coverage for up to 45 or sometimes 60 days abroad. This means that for shorter trips, you often don't need a separate travel insurance policy, as it covers emergency medical treatment, personal property theft while travelling, and other travel-related incidents. It's a handy perk that demonstrates just how holistic hemförsäkring aims to be as a personal safety net.
Finally, policies typically include assault protection (överfallsskydd) and crisis support (kristerapi). Assault protection provides financial compensation if you or a family member are victims of assault, covering specific injuries. Crisis support offers psychological help from a therapist after a traumatic event that your insurance covers, such as a serious accident, a burglary, or an assault. These additional layers of protection truly underscore the comprehensive nature of Swedish home insurance, extending beyond mere property to your personal well-being.
Why You Absolutely Need Hemförsäkring in Sweden (Even if Not Legally Required)
Unlike car insurance, hemförsäkring isn't legally mandatory in Sweden. No government body or law will fine you for not having it. However, many landlords or housing associations (BRF) will require you to have valid home insurance as part of your rental agreement. Even if they don't explicitly state it, taking the risk of living without it is simply reckless, especially for a newcomer.
Protecting Your Valuables from the Unexpected
Think about everything you own. Your laptop, phone, clothes, furniture, kitchen appliances, sentimental items, even your bicycle. If a fire rips through your building, a thief breaks in, or a burst pipe floods your apartment, how would you replace all of that? The cost would be astronomical. Hemförsäkring for your personal property, or lösöre, covers exactly this scenario. It provides financial compensation to replace your belongings, ensuring you're not left starting from scratch.
Let’s consider a hypothetical: you're enjoying a lovely fika at a café, and when you return home, you find your apartment door forced open. Your laptop, expensive camera, and some jewelry are gone. Without hemförsäkring, you'd have to shoulder the entire cost of replacing these items yourself. With it, after filing a police report and making a claim, your insurer would compensate you, minus your deductible (självrisk). The peace of mind alone is worth the monthly premium. The policy aims to replace lost items with new ones, or compensate you for the loss, often taking into account depreciation for older items.
The Critical Role of Liability and Legal Protection
This is where hemförsäkring truly shines as an essential protection for expats. Imagine this common scenario: you're cooking dinner, get distracted, and a small kitchen fire breaks out, damaging your apartment and perhaps even the ventilation system affecting a neighbor. Or, a washing machine hose comes loose, and water cascades down into the apartment below, ruining their ceiling and electronics. In these situations, your liability protection (ansvarsskydd) is your knight in shining armor. It covers the costs of damages you are deemed responsible for, potentially saving you from crippling debt.
It's not just about property damage either. What if your dog, usually a gentle giant, gets spooked on a walk and bites another person, requiring medical attention? Or your child accidentally knocks over a priceless vase in a friend's home? These are all situations where your ansvarsskydd would come into play, covering medical bills or compensation for damages. The Swedish legal system places a high value on responsibility, and these incidents, even if accidental, can lead to significant financial demands. Trying to navigate these claims in a foreign language and legal system without the backing of an insurance company would be a nightmare. Furthermore, the legal aid component, rättsskydd, can cover a large portion of your legal fees if you're involved in certain civil disputes, offering another layer of critical financial security.
The Hidden Benefits: Travel and Personal Security
As I mentioned earlier, the integrated travel insurance is a huge plus. Many expats travel frequently, whether for holidays or to visit family back home. Having up to 45 or 60 days of travel insurance automatically included with your hemförsäkring can save you the hassle and cost of buying separate policies for shorter trips. This coverage typically includes emergency medical care abroad, assistance with lost luggage, and even certain cancellations, providing a vital safety net when you're outside Sweden's borders. Before you book your next flight, it's always wise to check the specifics of your policy regarding travel, just to be sure.
Beyond travel, the personal security aspects like assault protection and crisis support are invaluable. While we all hope to never need them, knowing that your insurance provides financial compensation if you're a victim of a violent crime, or offers access to psychological counseling after a traumatic event like a burglary, adds an immense layer of comfort. It's about protecting your financial assets and your mental well-being when life takes an unexpected dark turn.
Navigating the Swedish Insurance Market: Choosing Your Provider
Choosing an insurance provider in Sweden can feel a bit daunting, especially when you're still grappling with the language and a new administrative system. However, there are several well-established companies, and increasingly, digital-first options that cater to the modern expat.
Major Players and What They Offer
Sweden has a strong and competitive insurance market with several large, reputable companies. The most common names you'll come across are:
- If: A Nordic insurance company, often seen as a traditional and reliable choice. They offer a range of policies and generally have good customer service.
- Folksam: Another very well-known Swedish insurer, often associated with collective agreements through unions or organizations. They have a wide range of offerings.
- Länsförsäkringar: This is actually a group of 23 local, customer-owned insurance companies, so service can vary slightly by region. They are known for their strong local presence and comprehensive services.
- Trygg-Hansa: Part of the Danish Tryg Forsikring group, they are a major player in Sweden with a focus on ease of use and good accessibility.
- Hedvig: A newer, digital-first insurer that has gained popularity, particularly among younger demographics and expats. They are known for their user-friendly app, English-speaking support, and a streamlined claims process.
- ICA Försäkring: Associated with the popular ICA supermarket chain, they offer competitive prices and often loyalty benefits for ICA cardholders.
When you're trying to set up your home, perhaps alongside getting your Getting Broadband and Mobile Service in Sweden, you might find that some providers are more adaptable than others, especially if you haven't received your personnummer yet.
Factors to Consider When Comparing Policies
It's tempting to just pick the cheapest option, but that's rarely the best strategy for insurance. A truly effective hemförsäkring needs to match your specific needs. Here are the crucial factors to weigh:
- Coverage amount (försäkringsbelopp): This is the maximum amount your insurer will pay out for your personal belongings. Do you have expensive electronics, valuable jewelry, or unique artwork? Ensure the försäkringsbelopp adequately covers the replacement cost of your most valuable items. If you have particularly high-value items, you might need a special add-on or a higher overall limit.
- Deductible (självrisk): This is the portion of a claim you pay out of pocket before the insurance kicks in. A lower deductible usually means a higher monthly premium, and vice-versa. Consider your financial comfort level: would you prefer to pay a bit more each month for a lower deductible in case of a claim, or save on premiums and pay more if something happens?
- Specific add-ons (tilläggsförsäkringar): Most standard policies are good, but you might want extra protection.
- Allrisk (drulle): Often called "clumsiness insurance" in English, this covers accidental damage or loss of your items, not just theft or fire. We'll delve deeper into this shortly.
- Extended travel insurance: If you travel frequently or for longer periods, you might need an extension beyond the standard 45-60 days.
- Bicycle insurance: If you have an expensive bike, especially a commuter one, standard coverage might not be enough.
- Valuable item insurance: For specific high-value items like watches, furs, or special electronics, you might need to declare them separately.
- Customer service in English: For many expats, this is non-negotiable. While most major companies have English-speaking staff, some excel at it more than others, with Hedvig being a prime example of a company that has embraced the expat market with English-first services.
- Online tools/apps: Do you prefer managing your policy and claims digitally? Many providers offer user-friendly apps and online portals.
- Membership benefits/discounts: Are you a member of a union, a student organization, or do you have a loyalty card with a particular supermarket? Check if you qualify for any discounts.
Here’s a quick overview of what some popular providers generally offer:
| Feature/Provider | If | Folksam | Länsförsäkringar | Trygg-Hansa | Hedvig | ICA Försäkring |
|---|---|---|---|---|---|---|
| Primary Focus | Broad market | Collective, Unions | Local, Customer-Owned | Accessible | Digital-First | Cost-Effective |
| English Support | Yes | Yes | Yes (local) | Yes | Excellent | Yes |
| Online/App | Good | Good | Good | Good | Excellent | Good |
| Travel Incl. | Standard | Standard | Standard | Standard | Standard | Standard |
| Drulle (Allrisk) | Add-on | Add-on | Add-on | Add-on | Often incl. | Add-on |
| Loyalty/Discounts | Various | Unions/org. | Local benefits | Various | Referrals | ICA card |
Remember, this table provides a general overview. Always get personalized quotes and read the specific policy terms (försäkringsvillkor) to ensure it meets your needs.
Getting Your Hemförsäkring: Practical Steps for Newcomers
Securing hemförsäkring should be high on your priority list when you arrive in Sweden, ideally right after you've sorted out your accommodation. However, like many things in Sweden, the personnummer often plays a central role.
What You Need to Apply (and the Personnummer Conundrum)
Most Swedish insurance companies prefer, or even require, that you have a personnummer (Swedish personal identity number) to sign up for a policy. This can be a real headache for newcomers, as Getting Your Personnummer: The Gateway to Swedish Healthcare can take several weeks or even months. Without this magic number, you might find some doors closed. It's a classic Swedish administrative hurdle, just like trying to Can I See a Doctor in Sweden Before I Get My Personnummer? or opening a bank account.
Don't despair though! Some providers are more flexible and understand the expat dilemma. Companies like Hedvig are known for being able to issue policies with just your passport number and a Swedish address, sometimes followed by an update with your personnummer once you receive it. Other traditional insurers might also be able to help if you contact them directly by phone or visit a local office, explaining your situation. Be prepared to provide:
- Your full name and date of birth
- Your current Swedish address: This is essential. Remember to officially Registering Your Move Flyttanmälan with Skatteverket as soon as you have a permanent address.
- Type of dwelling: Apartment (hyresrätt or bostadsrätt) or house (villa).
- Size of your home: In square meters.
- Your contact details: Phone number (perhaps one you got via Airalo's eSIM service, ensuring connectivity from day one) and email.
- Proof of identity: Usually your passport.
It's always worth contacting a few different providers directly to see their specific requirements and flexibility for those without a personnummer yet. The situation can sometimes change, and direct communication is key. You'll quickly discover that the Why You Need a Personnummer for Almost Every Financial Service in Sweden is not an exaggeration.
Understanding Your Policy and Making a Claim
Once you have your hemförsäkring, don't just put it in a drawer and forget about it. Take the time to understand what you've actually bought. The policy terms (försäkringsvillkor) can be extensive, but they contain all the details about what's covered, what's excluded, your deductible, and how to make a claim. If possible, request these terms in English or use a translation tool.
Here are some tips for managing your policy and making a claim:
- Document your valuables: Before anything happens, take photos or videos of your belongings, especially high-value items. Keep receipts for expensive purchases. This documentation is invaluable if you ever need to make a claim for theft or damage.
- Know your deductible: Understand your självrisk. This is the amount you'll pay yourself before the insurance company covers the rest.
- Read exclusions: Be aware of what your policy doesn't cover. For example, some policies have limitations on cash, certain types of jewelry, or damage caused by specific events (like extreme negligence).
- How to make a claim: If an incident occurs (theft, damage, accident):
- For theft: Immediately report it to the police (call 114 14 for non-emergencies, or visit a police station). You will need a police report number for your insurance claim.
- For damage (e.g., water, fire): Take photos of the damage, try to mitigate further damage if safe to do so, and contact your insurance company as soon as possible.
- Contact your insurer: Most companies have online forms or dedicated claims phone lines. Be ready to provide details of the incident, any police reports, and documentation of your losses. They will guide you through the process.
Setting up home insurance is part of the larger task of Setting Up Your Home in Sweden: Utilities, Internet, and Insurance, and getting it right from the start can save you a lot of heartache later.
Common Misconceptions and Advanced Tips for Expats
Navigating the nuances of Swedish insurance can be tricky, even for Swedes! As an expat, you might encounter specific misunderstandings or have questions that aren't immediately obvious. Let's tackle some of these head-on.
"My Landlord Has Insurance, So I'm Covered, Right?"
This is probably the single most common and dangerous misconception among new arrivals, particularly those in Renting a Home in Sweden: How the First- and Second-Hand System Works. As discussed earlier, a landlord's building insurance covers the structure of the property. It protects the landlord's investment in the physical building. It does not cover your personal belongings, nor does it cover your liability if you accidentally damage the apartment beyond normal wear and tear, or cause damage to another tenant's property.
Let’s be crystal clear: if you live in a rented apartment (hyresrätt or andrahand), your landlord's insurance covers their property, not yours. If you're renting a place, say, through a second-hand contract you found on a site like Spotahome, it's absolutely crucial that you understand the terms, as your personal hemförsäkring will be your only recourse if something happens to your things or if you inadvertently cause damage. Without hemförsäkring, if you cause a serious fire or flood, you could be personally liable for tens or hundreds of thousands of kronor in repair costs. This is also relevant if you have issues with your deposit; having liability coverage can help if there's a dispute over damage. Knowing How Do I Get My Deposit Back in Sweden? often involves ensuring you didn't cause damage not covered by your own insurance.
This distinction is key to understanding First-Hand vs Second-Hand Rental Contracts in Sweden: Key Differences, as the responsibility for your personal possessions and liability always rests with you, the tenant.
Allrisk (Drulle) Insurance: Is It Worth the Extra Cost?
Allrisk, often affectionately called drulleförsäkring (clumsiness insurance), is an optional add-on to your standard hemförsäkring. It covers sudden, unforeseen external events that cause damage or loss to your items, which wouldn't typically be covered by standard property protection. It's for those "oops" moments that aren't theft, fire, or major water damage.
Think of it this way:
- Standard home insurance: Covers your phone if it's stolen from your bag.
- Allrisk (drulle): Covers your phone if you accidentally drop it in the toilet, spill coffee on your laptop, or lose your keys (though key replacement usually has a high deductible).
Is it worth it? For many, yes. We all have moments of clumsiness. Dropping your expensive smartphone, shattering a glass tabletop, or accidentally ruining a favorite jacket are frustrating but common occurrences. Without allrisk, you'd pay for these damages entirely yourself. With it, you're covered (minus the självrisk). The peace of mind for these everyday mishaps can be well worth the slightly higher premium. However, be aware that there are usually limits on the compensation for allrisk claims, and the deductible might be higher than for other types of claims. Always check the specifics of the allrisk add-on with your chosen provider.
Special Considerations for Homeowners and Collective Bargaining
If you're not renting, but buying property in Sweden, the insurance landscape shifts slightly.
For those purchasing an apartment in a housing cooperative (bostadsrätt), you'll need bostadsrättsförsäkring. This is a specific type of hemförsäkring that not only covers your personal belongings and liability but also extends to cover the fixed installations and parts of the apartment you are responsible for maintaining, such as interior surfaces, kitchen fittings, and bathroom fixtures. Your bostadsrättsförening (BRF) usually has a collective building insurance, but that doesn't cover these internal parts that fall under your responsibility. Always check if your BRF's collective insurance includes a bostadsrättstillägg (bostadsrätt add-on) – if it does, you won't need to add it to your individual hemförsäkring. Understanding Bostadsrätt: Buying into a Swedish Housing Co-op and The Bostadsrättsförening BRF and Your Monthly Avgift Explained is crucial here.
If you're buying a detached house (villa), you'll need villaförsäkring. This is the most comprehensive type of home insurance, covering both the physical structure of the house (the building itself) and your personal belongings, as well as liability and all the other components of a standard hemförsäkring. It’s essentially a combined building and contents insurance policy.
Finally, for all types of hemförsäkring, always inquire about collective agreements (kollektivavtal). Many unions, professional organizations, or even employers have agreements with insurance companies that offer discounted rates or enhanced coverage. If you join a Swedish union (which I highly recommend for many reasons!), check if they offer insurance benefits through companies like Folksam or If. It’s a smart way to get quality coverage at a potentially lower price.
Disclaimer
The information provided in this guide is for general informational purposes only and does not constitute professional financial, legal, or insurance advice. While we strive to provide accurate and up-to-date information, the Swedish insurance landscape, regulations, and individual policy terms can change. Always consult directly with a qualified insurance provider or legal professional in Sweden to discuss your specific circumstances and obtain personalized advice. We are not liable for any decisions made based on the information presented here.