What Is a UC Credit Check and How Do I See My Score?
Arriving in Sweden with a "perfect" credit score from your home country only to be rejected for a basic mobile phone contract is a frustrating rite of passage. This guide explains exactly what a UC credit check is, why your international history doesn't follow you, and the specific steps you must take to see your own Swedish credit score.
What exactly is a UC credit check in Sweden
When you apply for anything involving a payment plan in Sweden—be it a mortgage, a credit card, or even a monthly gym membership—the provider will almost certainly "ta en UC." This refers to a credit disclosure performed by Upplysningscentralen (UC), the country’s leading credit-reporting agency. Owned by Sweden’s largest banks, UC acts as the central vault for financial reputations. Unlike some countries where you might have multiple equally weighted bureaus, UC is the absolute gold standard here. If your UC report looks "thin" or "weak," you will find it nearly impossible to navigate the local economy.
The most jarring realization for most newcomers is that Sweden is a "closed-loop" financial system. It does not matter if you had a 800+ FICO score in the United States or a stellar credit history in the UK. When a Swedish company runs a UC check, they are looking specifically at your Swedish history linked to your Personnummer. If you have only been in the country for a few months, the report will likely show zero income and no history, leading to an automatic rejection by the automated systems used by most retailers.
Every time a company performs this check, a record of the inquiry is saved. These are known as "förfrågningar," and having too many of them in a short period is a major red flag for lenders. I learned this the hard way when I tried to compare three different internet providers in one week; each one ran a check, and by the third one, I was flagged as a high-risk individual despite having a healthy bank balance. Understanding Your UC Credit Score: How It's Calculated and Why It Matters is essential to avoiding these early mistakes that can take a year to fall off your record.
How to see your Swedish credit score and report
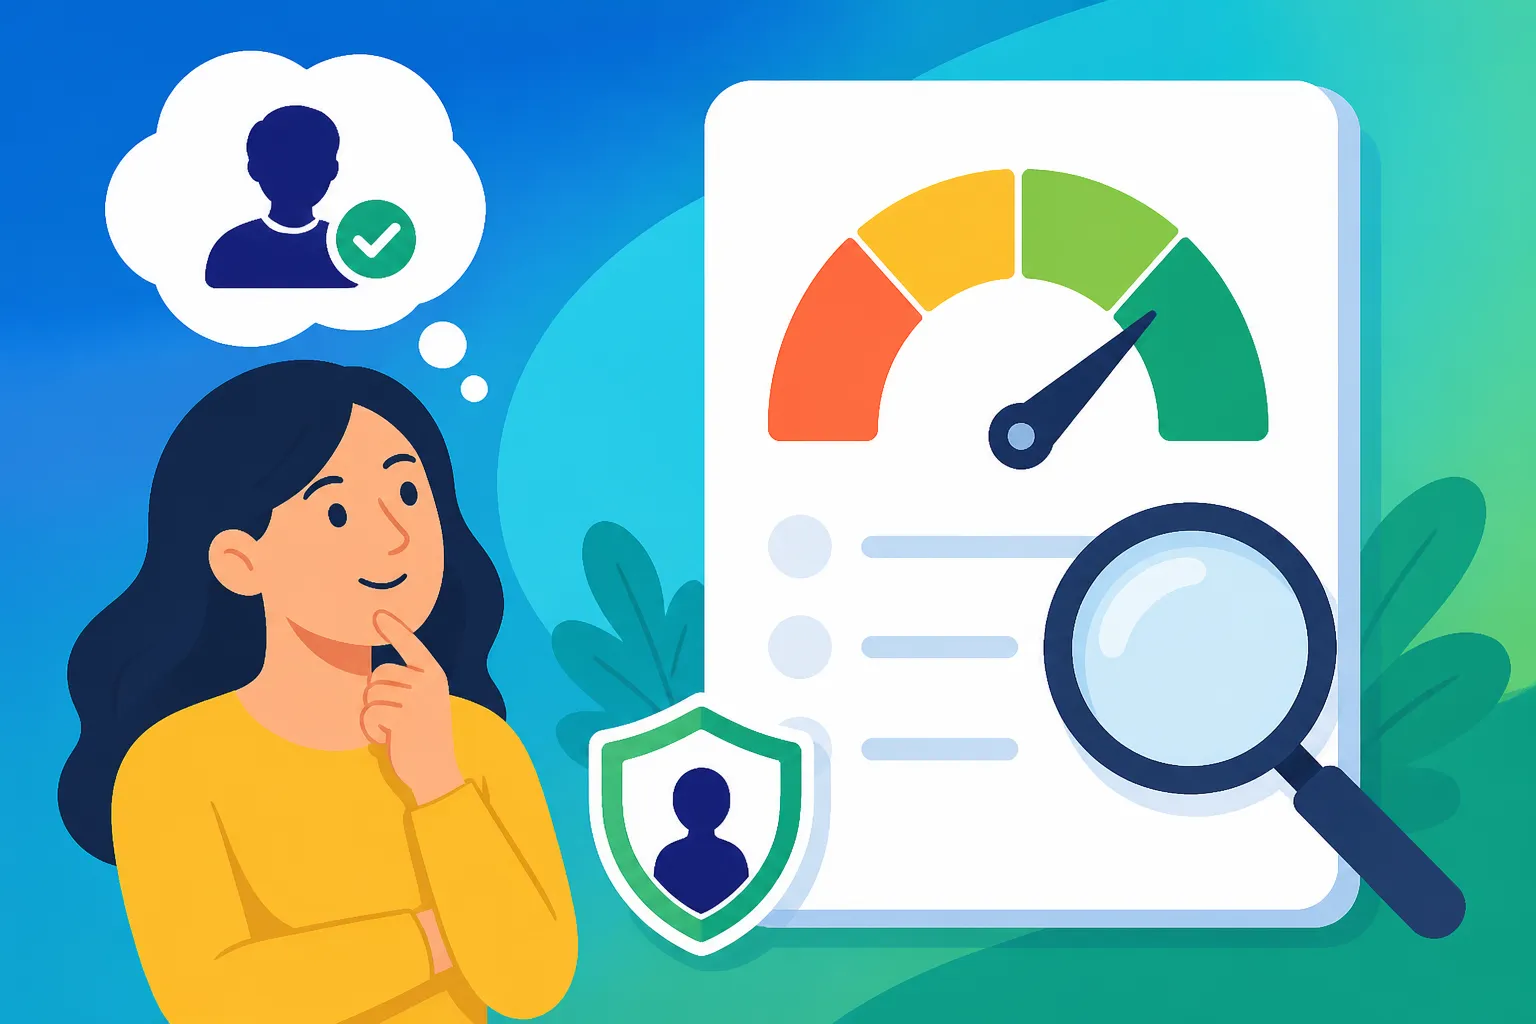
In the spirit of Swedish transparency, you have the right to see exactly what UC says about you. The primary way to do this is through a service called "Min UC," which is the consumer portal for the bureau. To access this, you will absolutely need to have Getting BankID: Sweden's Essential Digital Identity already sorted. Once you log in to MinUC.se, you can see your "Risk Forecast" (Riskprognos), which is a percentage indicating the likelihood of you being unable to pay your debts within a year. A score of 0.1% is considered excellent, while anything above 10% will make lenders very nervous.
If you don't want to pay for a full subscription, there is a free alternative worth mentioning. A service called Kivra, which many expats use for digital mail, often provides a basic overview of your credit data if a check has recently been performed on you. Additionally, there are apps like Kreddy that pull your UC data for free and give you a simplified "credit grade." While these are helpful, they don't always provide the granular detail you find in a full report, such as the specific dates of your historical income filings or a list of every company that has "searched" you in the last 12 months.
When you do access your report, pay close attention to the income section. UC pulls this data directly from Skatteverket (the Swedish Tax Agency). Because taxes are filed annually, there is often a massive lag. If you moved here in August, your income won't be officially "on the books" and visible to UC until the following summer. This is Why You Need a Personnummer for Almost Every Financial Service in Sweden is so critical; without that number and a full year of tax history, your credit report looks like a blank page. For those who are also managing taxes back in the US, using a specialist like Taxes for Expats can help you keep your global income reporting consistent, though it won't directly speed up the Swedish UC's data lag.
Factors that influence your Swedish credit score
Your Swedish credit score is driven by a very specific set of variables that differ slightly from the "credit utilization" focus common in other countries. In Sweden, your "Taxable Earned Income" (Taxerad inkomst) is the king of metrics. If your income fluctuates wildly, or if you have recently switched from a high-paying job to a lower-paying one, your Risk Forecast will likely increase. UC likes stability above all else. They also look at your "Total Debt" (Total skuldsättning), which includes everything from student loans to your mortgage.
Another massive factor is the "Payment Default" or "Betalningsanmärkning." This is the "scarlet letter" of the Swedish financial world. If you miss a bill and it goes through the debt collection process all the way to the state enforcement agency, you get a mark on your UC. This mark stays for three full years and will prevent you from renting an apartment or getting any form of credit. This is why it is so important to understand the process of Dealing with Kronofogden: Debt Enforcement in Sweden before you accidentally ignore a small invoice that could ruin your score.
Finally, your "Credit Limit History" matters. If you have several credit cards with high limits, even if you have zero balance on all of them, UC views that as "potential debt." If you have a 50,000 SEK limit on a card you never use, the system assumes you could spend that tomorrow, which affects your score. For newcomers, managing small initial costs is often easier via services like Wise, which allow you to hold and spend SEK without immediately needing to apply for local credit cards while your score is still fragile.
| Credit Bureau | Market Share | Common Use Case | Data Source |
|---|---|---|---|
| UC (Upplysningscentralen) | High | Mortgages, major loans, credit cards | Banks, Skatteverket, Lantmäteriet |
| Bisnode (Dun & Bradstreet) | Medium | Retail installments, phone contracts | Public records, smaller lenders |
| Creditsafe | Medium | B2B, smaller credit checks, rental checks | Public records, trade data |
Practical tips for managing your credit as an expat
Building credit in Sweden is a marathon, not a sprint. The first thing you should do after Opening a Bank Account in Sweden: A Step-by-Step Guide is to minimize the number of credit checks you allow. If a store clerk offers you a "10% discount if you open a store card," say no. That small discount is not worth the "förfrågan" that will sit on your UC report for a year. Many expats get rejected for a mortgage simply because they had six or seven "small" credit inquiries from trying to buy furniture on installment plans.
If you are a newcomer struggling to get a phone plan because of a thin UC report, try going to a physical store with your employment contract. Sometimes, a human manager can override the system if they see you have a permanent job (Tillsvidareanställning). You should also ensure you are registered correctly in the population register. The information UC holds is only as good as the data at Skatteverket. If your address is wrong, or if you haven't properly understood The Swedish Tax System Explained: Rates, Returns, and Filing, your UC report might not even generate correctly, leaving you in a bureaucratic limbo.
Consistency is your best friend. Pay every bill the moment it arrives in your digital mailbox (Kivra). Using Swish: How Sweden Pays Instantly for peer-to-peer payments doesn't affect your credit score, but it helps you manage your budget so you never miss an official invoice. If you are a US citizen, remember that your Swedish financial life is transparent to both countries; keeping your filings organized with Taxes for Expats ensures you don't run into issues that could eventually flag your accounts. Over time, usually after two full tax years, your UC score will naturally stabilize as the system sees a pattern of steady income and responsible payment.
If you are planning to buy a home, start monitoring your UC score at least 12 months in advance. Understand How Mortgages (Bolån) and the Amortisation Requirement Work in Sweden and see how your current debt-to-income ratio looks on paper. If you have any unused credit cards, close them. Each closed account reduces your "potential debt" and can marginally improve your Risk Forecast. For international transfers during the home-buying process, using Wise can save you a significant amount in fees compared to the big Swedish banks, though the bank will still want to see your UC report for the actual mortgage approval.
Disclosure
This guide is for informational purposes only and does not constitute financial, legal, or tax advice. Credit scoring systems and regulations in Sweden are subject to change. While we strive to provide accurate and up-to-date information, readers should always verify requirements with the official Upplysningscentralen (UC) website or consult with a qualified financial advisor in Sweden. Any mention of third-party brands is based on their general utility for expats and does not imply a guaranteed outcome for your specific financial situation.