Should I Choose a Fixed or Variable Mortgage Rate in Sweden?
Navigating the Swedish housing market can feel like deciphering ancient runes, and once you’ve finally secured a home, the next big hurdle is understanding mortgages. For many of us expats, the choice between a fixed or variable mortgage rate in Sweden isn't just a financial decision; it's a deep dive into an unfamiliar system, often leaving us wondering which path will offer the most peace of mind and financial stability. This guide aims to demystify these options, helping you make an informed choice that truly fits your unique situation.
Understanding the Swedish Mortgage Landscape: Rörlig vs. Bunden Ränta
When you sit down with a Swedish bank to discuss a mortgage, you'll inevitably encounter two main terms: rörlig ränta and bunden ränta. These are simply Swedish for variable and fixed interest rates, but in practice, they come with nuances that are crucial for us foreigners to grasp. It’s not just about the numbers; it’s about understanding the underlying philosophy and how it interacts with your life here.
What is a Variable Rate (Rörlig Ränta) in Sweden?
A variable rate, or rörlig ränta, is exactly what it sounds like: an interest rate that can change over time. In Sweden, this typically means your rate is reviewed and potentially adjusted every three months. This isn't like some countries where the rate can literally change day-to-day; there's a predictable cycle, but the rate itself is tied to market conditions and, most significantly, to the Riksbanken's (Sweden's central bank) policy rate.
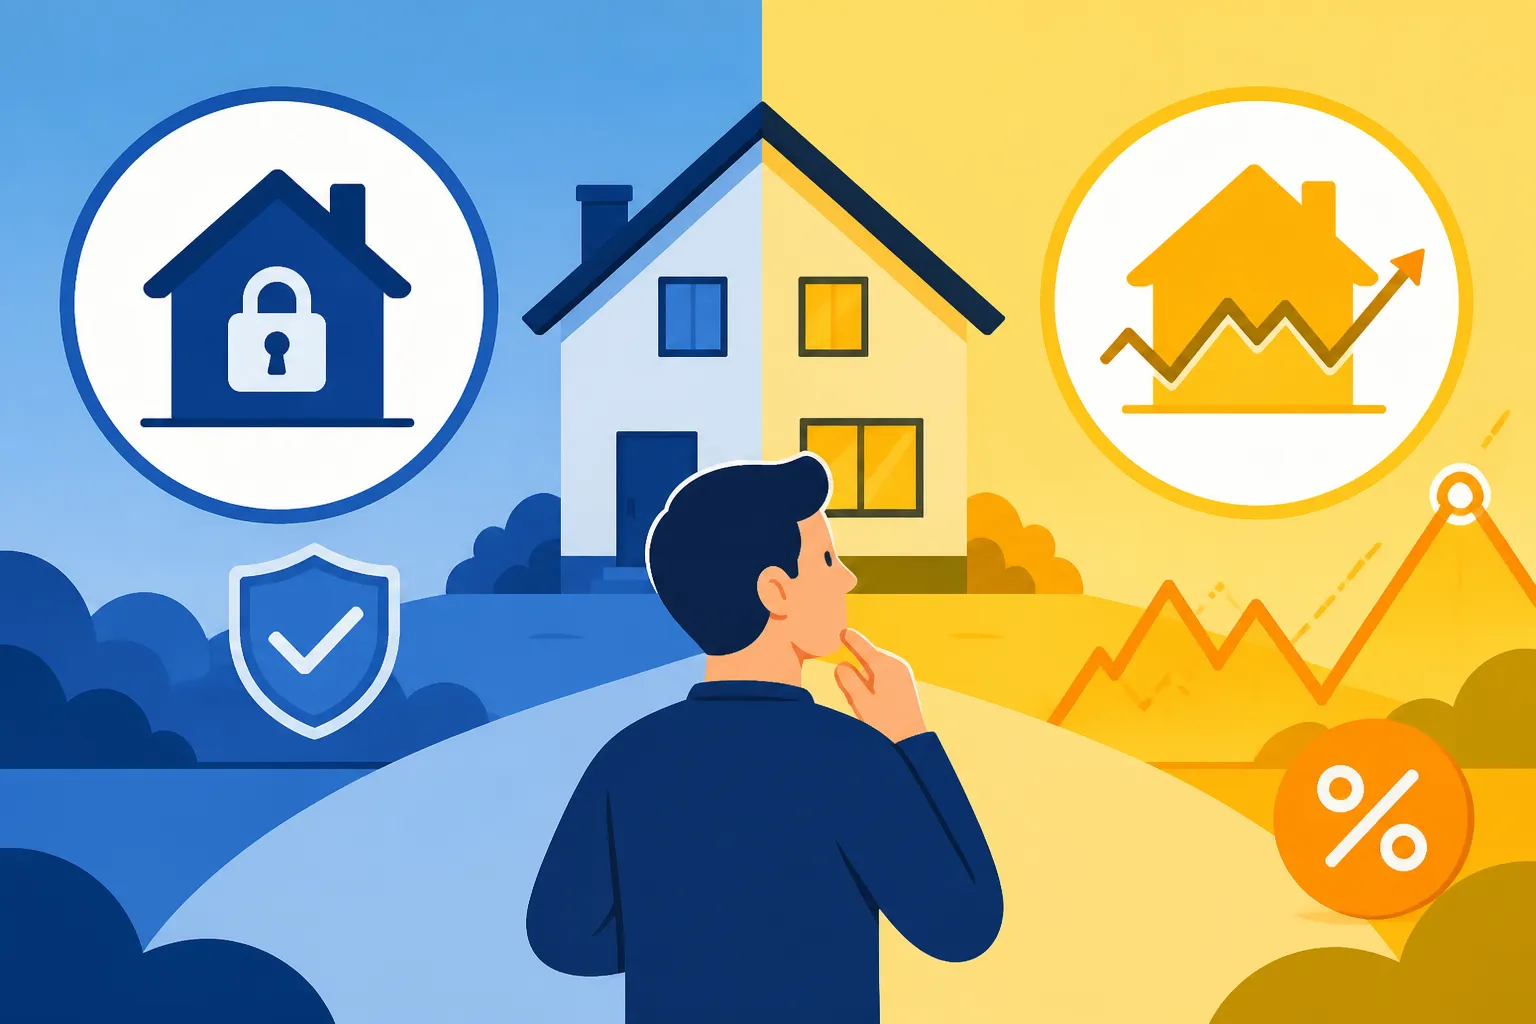
The beauty of a variable rate, for many, lies in its flexibility and the potential for lower costs. When the Riksbanken lowers its policy rate, your mortgage rate is likely to follow suit, leading to lower monthly payments. Imagine the relief during periods of declining interest rates – your disposable income goes up, and suddenly, that expensive trip home or an extra fika seems more feasible. However, this flexibility is a double-edged sword. When the Riksbanken decides to raise rates, your payments will also increase, and sometimes quite sharply. I remember when rates started creeping up a few years ago; suddenly, everyone with rörlig ränta was nervously checking the news, calculating how much their next payment would jump. It can be a real source of anxiety if you're not financially prepared.
For expats, the rörlig ränta can be appealing if you anticipate moving again in a few years or if you have a comfortable financial buffer. There are no penalties for repaying the loan early or making extra payments, giving you complete freedom to manage your mortgage as your circumstances change. This flexibility is a huge plus if you're still in that "figuring things out" phase of expat life. However, if your budget is tight and every krone counts, the unpredictability can be a major stressor. You need to be able to absorb potential increases without it derailing your finances. Think about it: if your rent suddenly jumped 500-1000 SEK a month, would you still be comfortable? That's the kind of scenario you need to plan for with a variable rate.
What is a Fixed Rate (Bunden Ränta) in Sweden?
On the other side of the coin, we have the fixed rate, or bunden ränta. With a fixed rate, you lock in your interest rate for a specific period, typically ranging from one year up to ten years, though 2, 3, or 5 years are most common. This means that regardless of what the Riksbanken does or how the market fluctuates, your mortgage payments for that portion of the loan remain exactly the same for the entire agreed-upon period.
The primary advantage here is absolute predictability. You know precisely how much you'll be paying each month towards your interest, making budgeting incredibly straightforward. This can bring immense peace of mind, especially if you're on a tight budget, prefer stability, or just don't want the added stress of monitoring economic news. It allows you to plan your finances with certainty, knowing that at least one major expense won't surprise you. This stability is often invaluable for families or those establishing a long-term life in Sweden. It can feel like a warm, cozy blanket shielding you from the cold winds of economic uncertainty.
However, this security comes at a price. Fixed rates are generally slightly higher than variable rates at the time of signing, as the bank builds in a premium for taking on the interest rate risk. More importantly, if you decide to break your fixed-rate contract early – for example, by selling your property, refinancing with another bank, or making significant extra repayments – you will likely incur a hefty penalty known as ränteskillnadsersättning. This penalty is designed to compensate the bank for the interest they lose because you're no longer paying the agreed-upon rate. It can be a significant sum, potentially thousands or tens of thousands of kronor, so it's a serious consideration if your plans for staying in Sweden are not yet set in stone. This ränteskillnadsersättning is a major deterrent against early changes, making bunden ränta less flexible by design.
Factors to Consider When Choosing Your Mortgage Rate
Choosing between a fixed and variable rate isn't a one-size-fits-all decision. It requires a thoughtful assessment of your personal circumstances, your outlook on the economy, and your long-term plans in Sweden. It’s like picking out clothes for a Swedish winter: you need to consider the current temperature, but also how long you’ll be outside and what the forecast says!
Your Personal Financial Situation and Risk Tolerance
This is perhaps the most critical factor. How stable is your income? Do you have a robust emergency fund that can comfortably cover several months of increased mortgage payments if rates were to rise? For many expats, particularly those new to the job market or with permits tied to specific employment, income stability might feel less certain than for a long-term resident. If your income has fluctuations, or if you're living paycheck to paycheck, a variable rate could introduce unbearable stress. You can read more about How Mortgages (Bolån) and the Amortisation Requirement Work in Sweden to understand the financial commitments involved.
Consider your personal risk tolerance. Are you the type of person who thrives on a bit of uncertainty and the potential for greater savings, or do you prefer absolute predictability, even if it means paying a bit more? There’s no right or wrong answer here, only what makes you sleep soundly at night. If the thought of your monthly payment changing unexpectedly fills you with dread, a fixed rate is probably a better fit for your mental well-being, even if it means missing out on potential rate drops.
Think about your future plans too. Are you planning to start a family, which might lead to changes in income during parental leave? Are you considering going back to school, reducing your income temporarily? These life events can make budget predictability paramount. On the other hand, if you're confident in your job security and have savings, the variable rate might offer attractive savings over time, especially when rates are low. Many expats find that managing their finances in a new country is complex enough without adding rate uncertainty. Platforms like Wise can be helpful for managing funds across borders, particularly for initial down payments or if you're moving money for other investments, giving you more control over your overall financial picture.
The Current Economic Climate and Interest Rate Outlook
Keeping an eye on the Riksbanken and broader economic trends is vital, particularly with a variable rate. The Riksbanken's policy rate (styrräntan) directly influences the commercial banks' mortgage rates. If inflation is high, the Riksbanken is more likely to raise rates to cool down the economy. Conversely, during economic slowdowns or periods of low inflation, they might lower rates. You can delve deeper into How Does the Riksbank's Interest Rate Affect My Mortgage? to grasp this connection.
However, predicting interest rate movements is notoriously difficult, even for economists! While you don't need to become a central bank expert, understanding the general sentiment and forecasts can guide your decision. Major banks often publish their own interest rate forecasts. If the consensus points towards stable or falling rates, a variable rate might look more attractive. If rising rates are on the horizon, fixing your rate could protect you.
It's also important to remember that fixed rates are often priced higher than variable rates precisely because they factor in the bank's expectation of future rate changes. So, while you might lock in a rate today that seems higher than the current variable rate, it could prove to be a good deal if variable rates climb significantly during your fixed period. Some borrowers regret fixing when rates subsequently dropped, and others celebrate fixing just before a series of hikes. It’s a gamble, but one you can make more informed by paying attention to the news. For a broader financial overview, consider resources like Taxes for Expats to understand how potential capital gains or losses from your property might interact with your tax obligations, especially if you're considering the economic implications of selling your home later.
The Length of Your Stay in Sweden and Future Plans
How long do you realistically see yourself owning this property in Sweden? If you envision staying for many years, perhaps even decades, then a fixed rate for a longer period (e.g., 5 or 10 years) offers maximum stability and predictability. You might pay a bit more initially, but you're shielded from market volatility for a significant chunk of time.
Conversely, if your stay in Sweden is more uncertain – perhaps tied to a temporary work contract, or you're unsure if Sweden is your permanent home – then the flexibility of a variable rate might be more appealing. As mentioned earlier, breaking a fixed-rate contract early can result in the ränteskillnadsersättning penalty. If you think there's a good chance you'll sell your property within a few years, a variable rate avoids this potentially costly exit fee. This is a common dilemma for many of us who are still adapting to life here and aren't sure where the future will take us.
Also, consider life changes. Do you anticipate needing to upsize or downsize your home in the near future? Will a new job require you to move to a different city? These are all scenarios where the ränteskillnadsersättning associated with a fixed rate could become a significant financial burden. It’s essential to be honest with yourself about your long-term commitment to both the property and to Sweden itself.
Practical Considerations and Hybrid Strategies
Beyond the fundamental choice, there are several practical aspects of Swedish mortgages that can influence your decision and help you manage your financial commitments more effectively. Knowing how to negotiate, exploring hybrid options, and understanding refinancing are key tools in your expat financial toolkit. For a comprehensive overview of financial life, check out Money and Finance in Sweden: A Complete Guide for Foreigners (2027).
Negotiating Your Mortgage Rate and Bank Options
This might come as a surprise if you're from a country where mortgage rates are pretty much "take it or leave it," but in Sweden, you are absolutely expected to negotiate your mortgage rate! The rates advertised by banks are often just a starting point. Don't be shy; banks want your business, and they are often willing to offer better rates, especially if you have a good credit history (Your UC Credit Score: How It's Calculated and Why It Matters is relevant here) and other banking services with them.
It's not just about negotiating with your current bank. It's highly recommended to get offers from several different banks. The major players like Swedbank, SEB, Handelsbanken, and Nordea are obvious choices, but don't overlook challenger banks or niche mortgage providers who might offer more competitive rates or better terms. Many banks also have "green mortgages" with slightly lower rates if your property meets certain energy efficiency criteria. This can make a tangible difference over the life of the loan.
Presenting offers from competing banks is your strongest negotiation tactic. You can say, "Bank X offered me Y% – can you match or beat that?" This is a perfectly normal and expected part of the process in Sweden. Mortgage brokers (bolånemäklare) can also be incredibly helpful here. They work with multiple banks on your behalf, comparing offers and often securing rates you might not get on your own. This service is usually free for you, as the brokers are paid by the banks. They can be invaluable, especially if your Swedish isn't fluent or you're new to the system. For more guidance, see Choosing a Bank in Sweden: Swedbank, SEB, Handelsbanken, and Nordea.
The Hybrid Approach: Mixing Fixed and Variable Rates
For those who find themselves torn between the flexibility of a variable rate and the security of a fixed rate, Sweden offers an excellent solution: the hybrid mortgage. This approach allows you to divide your total mortgage into multiple parts, each with a different interest rate binding period.
For example, you could fix 50% of your mortgage for 3 years to ensure a stable base payment, while keeping the other 50% on a variable rate to take advantage of potential rate drops. Or, you could have a third of your loan on a 1-year fixed rate, another third on a 5-year fixed rate, and the final third on a variable rate. This strategy diversifies your risk and gives you more control. If variable rates drop, you benefit from part of your loan becoming cheaper. If rates rise, a significant portion of your loan remains stable.
The hybrid approach provides a "best of both worlds" scenario for many. It reduces the overall risk of dramatic fluctuations while still allowing you some flexibility. It also staggers the renegotiation dates, so you don't have your entire mortgage coming up for renewal at once, which could be financially overwhelming if rates happen to be high at that specific moment. Discussing this option with your bank is crucial, as they can help you structure the split in a way that aligns with your financial comfort zone and future outlook.
Refinancing and Early Repayment Penalties (Ränteskillnadsersättning)
Refinancing, or omlån, involves taking out a new mortgage to pay off your existing one, often to secure better terms or a lower interest rate. This is a common practice in Sweden, but it comes with a significant caveat if you have a fixed-rate mortgage: the ränteskillnadsersättning.
As we touched upon earlier, if you decide to refinance a fixed-rate mortgage before its term is up, the bank will charge you this penalty. It compensates them for the interest income they lose by you breaking the contract. The calculation is typically based on the difference between your fixed rate and the current market rate for the remaining term of your loan, discounted to present value. Essentially, if you locked in a rate of 3% and market rates are now 2%, the bank charges you for that 1% difference over the remaining years of your contract. This can make refinancing a fixed-rate mortgage an expensive endeavor.
However, if you have a variable rate, you can refinance at any time without penalty. This is another key advantage of the rörlig ränta. Even with a fixed rate, there are specific situations where the ränteskillnadsersättning might not apply, such as if you sell your property and the buyer takes over your existing loan (though this is less common). Before making any decisions about refinancing or selling with a fixed rate, always contact your bank to get a precise calculation of the potential ränteskillnadsersättning. It's vital to factor this into your financial planning.
| Feature | Variable Rate (Rörlig Ränta) | Fixed Rate (Bunden Ränta) | Hybrid Rate |
|---|---|---|---|
| Rate Changes | Typically every 3 months, tied to Riksbanken's policy rate. | Stays constant for the agreed period (e.g., 1, 3, 5 years). | Parts fixed, parts variable; changes only on variable portion. |
| Predictability | Low; monthly payments can fluctuate. | High; monthly payments are stable and predictable. | Moderate; a portion is stable, another fluctuates. |
| Flexibility | High; no penalty for early repayment or extra payments. | Low; penalty (ränteskillnadsersättning) for early changes. | Moderate; flexible on variable portion, restricted on fixed. |
| Cost Potential (Low Rates) | Potentially lower total cost if rates remain low or fall. | Higher initial cost, but stable; might miss out on drops. | Balances potential savings with stability. |
| Cost Potential (High Rates) | Higher total cost if rates rise significantly. | Protection against rising rates, locking in current cost. | Protects part of the loan from rises, exposes the rest. |
| Ideal For | Risk-tolerant, good financial buffer, short-term plans. | Risk-averse, strict budget, long-term stability sought. | Those seeking a balance of security and flexibility. |
When you're trying to figure out your overall financial picture in Sweden, including taxes on your property, capital gains if you sell, or just managing your income, consulting services like Taxes for Expats can provide specialized advice for us foreigners. They understand the intricacies that often trip up newcomers. And for sending or receiving money across borders, perhaps for your down payment or other investments, Wise is often described as efficient and transparent, which is a godsend when you're dealing with different currencies and fees.
The decision between fixed and variable mortgage rates is a deeply personal one, intertwined with your financial comfort, your outlook on the economy, and your life plans in Sweden. Take your time, weigh the pros and cons carefully, and don't hesitate to consult with multiple banks and perhaps even an independent mortgage broker. It's one of the biggest financial decisions you'll make here, so getting it right is worth the effort.
Disclaimer
Please remember that I am an expat blogger sharing personal experiences and general advice. I am not a financial advisor, and the information provided here is for informational purposes only. Mortgage terms, rates, and economic conditions in Sweden can change rapidly. Always consult with a qualified financial advisor and specific Swedish banks to get personalized advice tailored to your individual financial situation before making any decisions regarding your mortgage.