How Sweden’s Public Pension (Allmän Pension) Is Built
Most foreigners moving to Sweden view the monthly deductions on their payslip as a confusing black hole of high taxation, often fearing that their contributions will vanish if they decide to leave the country. This guide demystifies the Swedish public pension system, explaining exactly how your "Orange Envelope" is calculated and how your years in Sweden secure your future.
The Architecture of Allmän Pension
When you first arrive in Sweden and receive your first paycheck, you might be overwhelmed by the complexity of the deductions. However, it is essential to understand that the Swedish pension system is not a monolithic pot of money. It is a sophisticated, three-tiered structure designed to provide a baseline of security regardless of how the stock market performs. The "Allmän Pension" is the foundation of this system, managed by the Swedish Pensions Agency (Pensionsmyndigheten).
The Three Pillars of the Public System
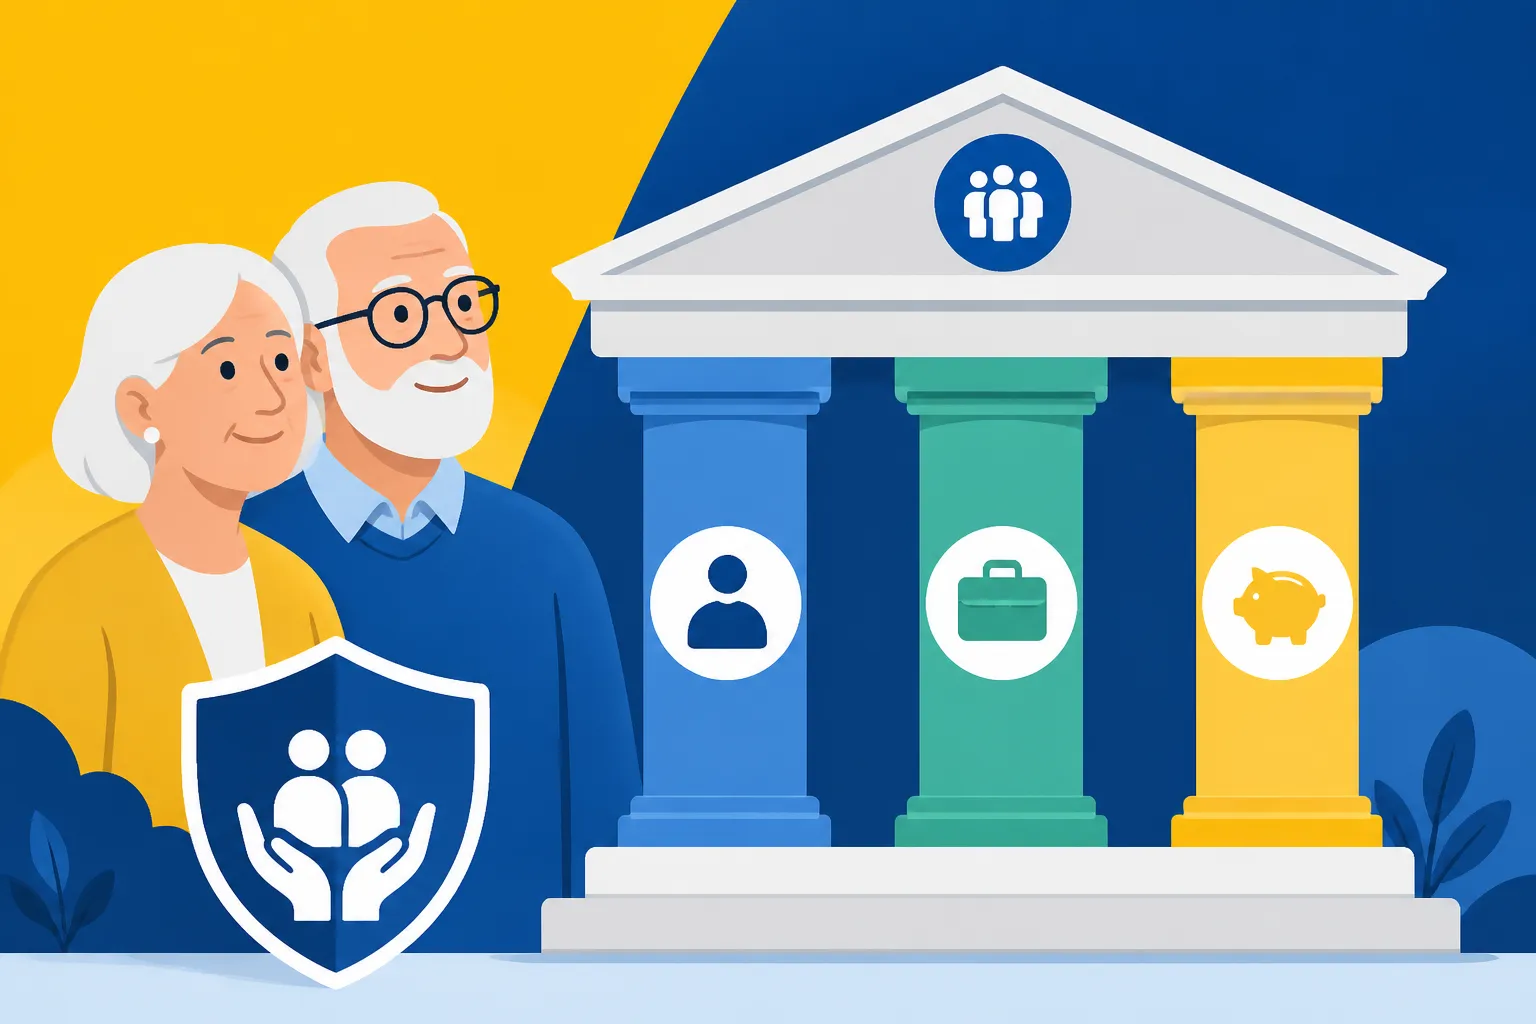
The public pension is built primarily on your income, but it also includes a safety net for those who have had lower earnings. The first pillar is the Inkomstpension (Income Pension), which follows a "pay-as-you-go" model. The second is the Premiepension (Premium Pension), which allows for individual investment choices. Finally, the Garantipension (Guarantee Pension) serves as a floor for those with little to no earned pension history in Sweden.
Understanding these distinctions is vital because each part behaves differently when you eventually retire. For instance, while you can influence your Premiepension by choosing specific funds, your Inkomstpension is tied strictly to the overall economic growth and wage development in Sweden. This balanced approach ensures that even if one part of the economy falters, your entire retirement fund isn't at risk.
Why You Need a Personnummer for Your Pension
The entire system is digitized and linked to your personal identity number. Without it, the Swedish Pensions Agency cannot track your contributions accurately over time. If you are still in the early stages of your move, you should prioritize Why You Need a Personnummer for Almost Every Financial Service in Sweden to ensure your work history is being recorded from day one. Every krona you earn after receiving this number starts building your future "Orange Envelope."
The Relationship Between Tax and Pension
Many expats mistakenly believe that the public pension is a separate "pot" they pay into like a private insurance scheme. In reality, it is funded by the "employer contributions" (arbetsgivaravgifter) that your company pays on top of your gross salary. While you see your net income after tax, your employer is actually contributing 18.5% of your pensionable income toward this public system. This is a crucial detail when Understanding Your Swedish Payslip and Preliminärskatt because it highlights that the cost of your future security is largely borne by the employer, though it is fundamentally tied to your labor.
The Accumulation Phase How Your Income Becomes a Pension
The most critical concept in the Swedish system is the "Pensionsgrundande Inkomst" (PGI), or pensionable income. This is the figure upon which your 18.5% contribution is calculated. However, the calculation isn't as simple as taking your gross salary and multiplying it. There are specific floors and ceilings that every expat should be aware of to maximize their retirement planning.
Understanding the Pensionable Income Ceiling
Sweden has a cap on how much of your income counts toward your public pension. For 2026, this cap is set at 7.5 "Income Base Amounts" (inkomstbasbelopp). If you earn above this threshold, any income beyond that point does not contribute further to your public pension. This is a common point of frustration for high-earning expats who assume their massive tax bills are resulting in an equally massive public pension.
When you hit this ceiling, the focus shifts to your occupational pension (tjänstepension), which is often where the real growth happens for professionals. If you are in this bracket, it is wise to consult services like Taxes for Expats to ensure you are balancing your Swedish obligations with any retirement accounts you might still hold in your home country.
Credits for Non-Work Periods
One of the most empathetic aspects of the Swedish system is that it recognizes that life isn't just about working 40 hours a week for 40 years. You earn pension credits even when you aren't "working" in the traditional sense. For example, years spent at home with young children, periods of mandatory military service, or time spent studying with support from CSN all contribute toward your PGI.
This "social" accumulation ensures that parents, particularly mothers who might take longer parental leave, are not unfairly penalized in their old age. For expats, this means that even if you take a break to learn Swedish or care for a newborn, your pension pot continues to grow. This is why How Sweden's Tax-Funded Healthcare Works: Regions, Costs, and Coverage and the broader social welfare state are so intrinsically linked; the system values your presence in the society, not just your output in the office.
The Role of the AP Funds
The 16% of your income that goes into the Inkomstpension isn't just sitting in a bank account. It is partially managed by the "AP-fonderna" (AP Funds), which are massive state-owned buffer funds. These funds invest in global markets to ensure that the system remains solvent even as the Swedish population ages. For the curious expat, looking into how these funds are invested can provide peace of mind that the Swedish state is managing its long-term liabilities with professional rigor.
Navigating the Premium Pension and the Famous Orange Envelope
While 16% of your contributions go to the general income pension, the remaining 2.5% goes into the Premiepension (PPM). This is the only part of the public system where you have direct control over where the money is invested. Every year, usually in March, the "Orange Envelope" (Orange kuvertet) arrives in your mailbox (or digital mailbox like Kivra), detailing exactly how much you have accumulated.
Making Your Fund Choices
You can choose to invest your PPM in up to five different funds from a vast list approved by the Swedish Pensions Agency. If you do nothing, your money is automatically invested in the default option: AP7 Såfa. Interestingly, many financial experts in Sweden suggest that the default fund is actually one of the best-performing options available, as it uses a lifecycle approach—taking more risks when you are young and gradually moving toward safer investments as you approach retirement.
If you are someone who enjoys Saving and Investing in Sweden: ISK, Funds, and the Stock Market, you might find the PPM choices a fun way to diversify your portfolio. You can switch funds at any time through the Pensionsmyndigheten website without any tax consequences, which is a significant advantage compared to private trading.
The Impact of Fees on Your PPM
One of the veteran tips for any expat is to watch the management fees on the funds you choose within the PPM system. Because the state negotiates these fees on behalf of millions of residents, they are often significantly lower than the fees you would pay as a private individual. Even a difference of 0.5% in fees can result in hundreds of thousands of kronor in difference by the time you retire.
Reading the Orange Envelope Without Panic
The first time you receive the Orange Envelope, the numbers might look small, especially if you have only been in Sweden for a year or two. Don't panic. The document provides a forecast based on several scenarios: if the economy grows by 2% or 0%, and if you continue to earn your current salary. It is a tool for long-term planning, not an immediate bank balance. If you struggle to interpret the Swedish terminology in the envelope, The Swedish Tax System Explained: Rates, Returns, and Filing guide can help clarify some of the overlapping financial terms.
The Guarantee Pension and the Social Safety Net
The Garantipension is Sweden’s way of ensuring that no one who has lived in the country for a significant portion of their life falls into poverty in old age. It is a residence-based benefit, meaning it isn't strictly tied to how much you have worked, but rather how long you have lived in Sweden.
Eligibility and the 40-Year Rule
To receive a full guarantee pension, you generally need to have lived in Sweden for 40 years between the ages of 16 and 64. If you have lived here for less time, the amount is reduced proportionally. For many expats who arrive mid-career, they will only ever qualify for a fraction of the guarantee pension. However, this is usually offset by the income pension they earn through their professional salary.
It is important to note that the guarantee pension is "tested" against your earned income pension. If your earned pension is high enough, your guarantee pension will be zero. It is truly a safety net for those who, for various reasons, were unable to build a substantial work-based pension.
Special Rules for EU/EEA Citizens
If you have moved to Sweden from another EU or EEA country, the rules are more favorable. You can often count years of residence or insurance in other member states toward the eligibility requirements for the Swedish guarantee pension. This is part of the broader EU coordination of social security systems. If you find yourself navigating these complex cross-border rules, obtaining advice from specialists like Taxes for Expats can be invaluable, as they understand the nuances of international treaties.
The Minimum Living Standard
The goal of the Garantipension is to provide a "skälig levnadsnivå" (reasonable standard of living). It is often supplemented by other benefits like "Bostadstillägg" (housing supplement for pensioners) if the pension alone isn't enough to cover rent. As a newcomer, you likely won't need to worry about this for decades, but it is a testament to the empathy of the Swedish system that such a floor exists.
Expat Logistics Moving Away and Managing Your Swedish Pension
One of the most frequent questions expats ask is: "What happens to my money if I leave Sweden?" The good news is that you do not lose your earned public pension. It stays in the Swedish system, accruing interest and value based on the Swedish economy, until you reach retirement age.
Claiming Your Pension from Abroad
When you reach retirement age (currently transitioning toward 64-67 depending on your birth year), you can apply to have your Swedish pension paid out to you, regardless of where in the world you live. Sweden has social security agreements with many countries, making this process relatively seamless. However, you will need to prove your life status annually (levnadsintyg) to ensure the payments continue.
When the time comes to transfer those funds, using a service like Wise can save you a significant amount in currency conversion fees. Traditional banks often charge high margins on the SEK to USD or EUR conversion, whereas Wise offers the mid-market rate, ensuring more of your hard-earned Swedish pension actually reaches your pocket in your home country.
Tax Implications: The SINK Tax
If you live abroad and receive a Swedish pension, you are generally subject to a special income tax for non-residents known as SINK (Statlig inkomstskatt för utomlands bosatta). Currently, this is a flat rate of 25%, and you don't need to file a full tax return in Sweden for it. For many, this is a simpler and cheaper option than ordinary taxation.
However, your home country might also want to tax that income. This is where double taxation treaties come into play. Consulting with Taxes for Expats can help you determine if you should opt for the SINK tax or if ordinary taxation would be more beneficial based on your total global income. For more on how these taxes work while you are still working, check out Income Tax in Sweden: Municipal, State, and the SINK Regime.
The "Use It or Lose It" Myth
There is a persistent myth that if you don't work for at least three or five years, you get nothing. This is false for the income-based part of the pension. Even if you worked in Sweden for only six months, you have earned pension credits. The "three-year rule" often cited actually refers to certain residence-based benefits or specific older regulations. Your PGI is yours to keep. You can track this by Getting BankID: Sweden's Essential Digital Identity and logging into the Pensionsmyndigheten portal even after you have moved abroad.
Digital Tools and Financial Planning for Newcomers
Sweden is one of the most digitally advanced nations on earth, and this extends to how you manage your financial future. You should not wait until you are 60 to start looking at your pension forecast.
MinPension.se: The Ultimate Overview
While the Pensionsmyndigheten website covers the public pension, most workers in Sweden also have an occupational pension (tjänstepension) through their employer. To see the whole picture, you should use MinPension.se. This site aggregates your public pension, your occupational pensions from various employers, and any private savings you might have.
It provides a "pension simulator" where you can see how much you would receive monthly if you retired at 62, 65, or 70. It also shows you how a change in salary would affect your future. To access this, you will need to have already gone through the process of Opening a Bank Account in Sweden: A Step-by-Step Guide so that you have the necessary BankID for secure login.
Why You Should Also Save Privately
While the Allmän Pension is robust, it is designed to replace only about 45-55% of your final salary. To maintain your lifestyle, the occupational pension is supposed to bridge the gap to about 70-80%. However, for many expats who arrive later in life, there is a "pension gap" because they haven't contributed for the full 40 years.
This makes private saving essential. Whether you choose to invest in a global index fund through an ISK or simply save in a high-interest account, taking control early is key. When moving money between your international accounts to fund these investments, Wise remains the most transparent way to handle the transfers without losing money to hidden bank spreads.
Comparative Overview of Public Pension Components
| Component | Source of Funding | Portability (Moving Abroad) | Investment Control |
|---|---|---|---|
| Inkomstpension | 16% of PGI | Fully Portable | None (tied to economy) |
| Premiepension | 2.5% of PGI | Fully Portable | High (choose your funds) |
| Garantipension | State Taxes | Restricted (mostly EU/EEA) | None (safety net) |
Summary of Next Steps for New Expats
- Verify your PGI: Check your first few payslips to ensure your employer is correctly reporting your income. Cross-reference this with the information in Understanding Your Swedish Payslip and Preliminärskatt.
- Log into Pensionsmyndigheten: Use your BankID to see your current standing. Even if you've only been here a month, the system should show your registration.
- Check your PPM funds: Decide if you want to stay in the default AP7 Såfa fund or pick your own. Most veterans suggest the default is excellent for those who aren't professional investors.
- Plan for the gap: If you arrived in Sweden after age 30, use MinPension.se to see your projected shortfall and start a private savings plan.
- Keep your records: Even if you leave Sweden, keep your Personnummer and BankID (if possible) active for as long as you can to monitor your accounts. If you relocate, ensure you update your address with the Swedish Tax Agency (Skatteverket) so your Orange Envelope finds you.
Building a life in a new country is hard enough without worrying about your old age. The Swedish public pension system is a remarkably fair and transparent machine once you understand the levers. By staying informed and using tools like Wise for your cross-border needs and Taxes for Expats for your annual filings, you can enjoy the Swedish "fika" culture today while knowing your future self is well-provided for.
Important Disclaimer
The information provided in this guide is for educational and informational purposes only and does not constitute professional financial or legal advice. Pension rules and tax thresholds in Sweden are subject to change by the Swedish government and the Pensions Agency. Always consult with a certified financial advisor or a tax professional regarding your specific situation, especially concerning cross-border tax liabilities and retirement planning. For the most current rates and regulations, visit the official Pensionsmyndigheten website.