Your UC Credit Score: How It’s Calculated and Why It Matters
Imagine walking into a phone store on Drottninggatan in Stockholm, ready to sign up for a new contract, only to be told "the system says no." You have a stable job, a decent salary, and you’ve never missed a bill in your life—back home. In Sweden, your financial past doesn't travel with you. This guide explains how the UC credit score functions as the invisible gatekeeper to your new life and how to master it.
What is a UC Credit Score and Why Should You Care?
When you first land in Sweden, you are, for all intents and purposes, a financial ghost. You might have arrived with a suitcase full of dreams and a signed contract from a major tech firm in Kista, but to the Swedish credit system, you don't exist until you are "folkbokförd" (registered in the population register). The entity that manages this digital shadow is UC, or Upplysningscentralen.
The Role of Upplysningscentralen in Swedish Life
UC is not a government agency, though it often feels like one because of how much power it wields. It is actually Sweden's leading business and credit information agency, originally owned by the major banks like Nordea, SEB, and Swedbank. It acts as a central repository for your financial behavior. Every time you apply for something that involves "kredit"—be it a Klarna "pay later" purchase, a gym membership, or a mortgage—the provider will likely pull a "UC-upplysning" on you.
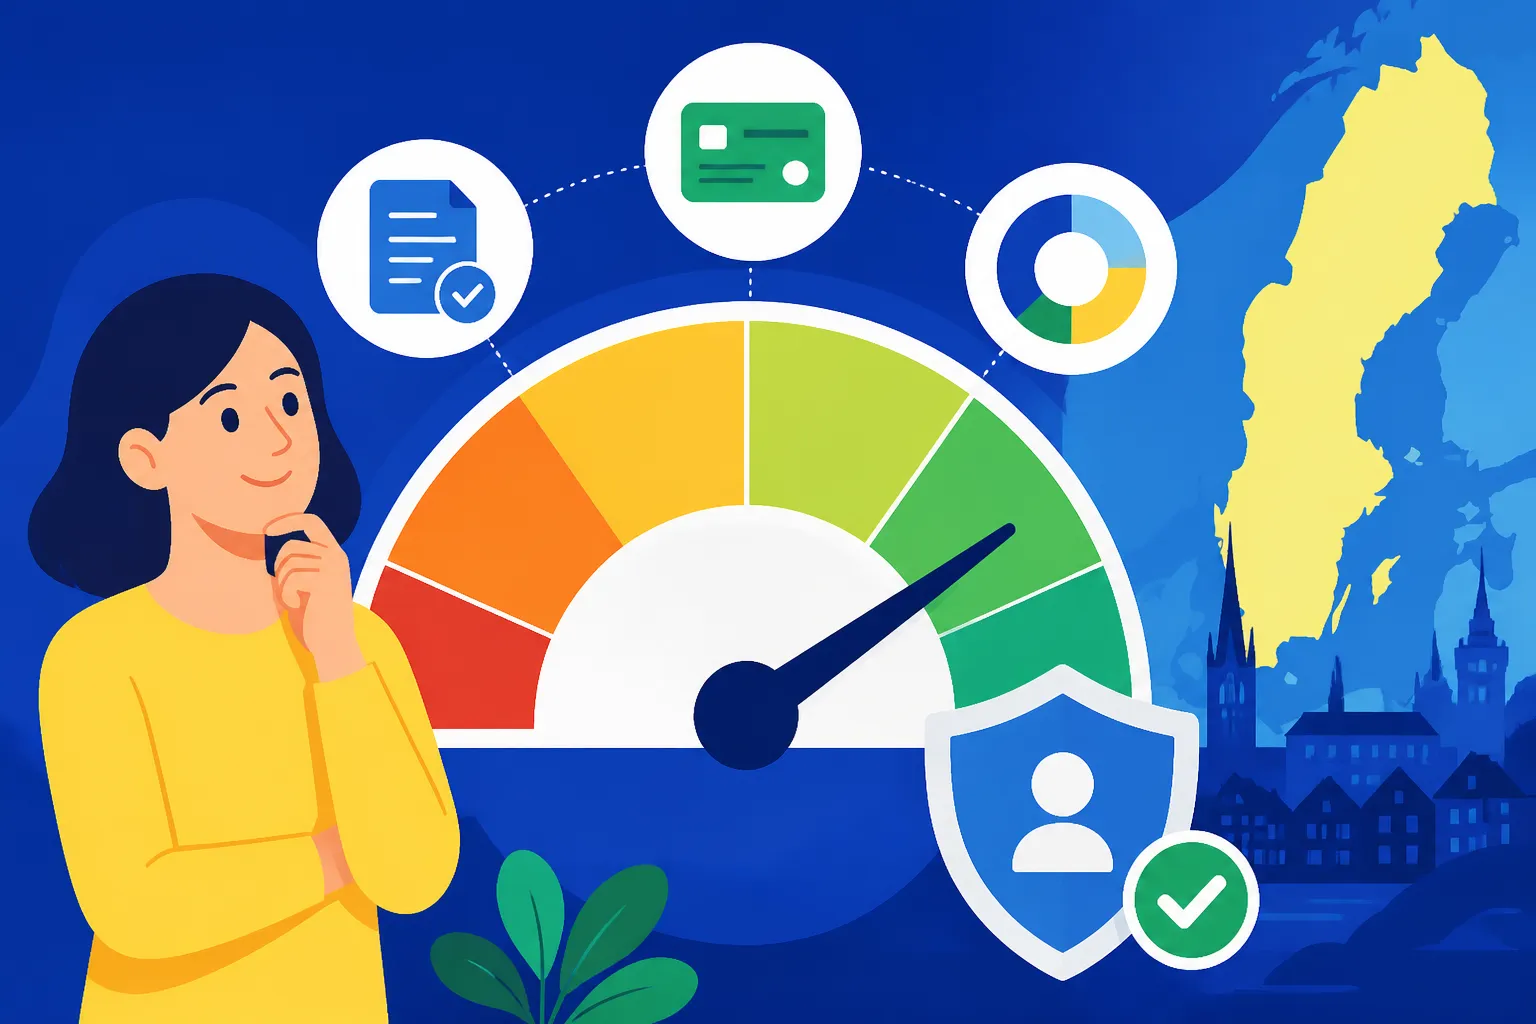
This report tells the lender everything: your declared income from the last two years, your current debts, your marital status, and most importantly, your "Riskprognos" (risk forecast). This is a percentage that represents the likelihood of you failing to pay a debt within the next 12 months. If that number is too high, you’ll find doors closing before you even get a chance to explain your situation.
When Your UC Score is Checked
It isn't just about bank loans. In Sweden’s highly digitized and cashless society, credit checks are everywhere. If you want to rent an apartment from a professional landlord (a " förstahandskontrakt"), they will check your UC. If your score is marred by a payment default, they might reject your application instantly, regardless of your current income.
Even simple things like getting a home internet connection or a post-paid SIM card require a check. If you’ve just arrived, Opening a Bank Account in Sweden: A Step-by-Step Guide is your first hurdle, but even after that, your lack of a UC history can make these everyday tasks surprisingly difficult. I remember my first month in Gothenburg, trying to get a basic internet package; I had to pay a massive deposit upfront simply because I hadn't been in the system long enough for a UC score to generate.
The Invisible Barrier for New Arrivals
The biggest frustration for expats is the "lag." UC bases its data largely on your filed tax returns. This means if you move to Sweden in July 2024, your first full year of income won't be reported to the tax agency (Skatteverket) until early 2025, and it won't show up on a UC report until the middle of that year.
For nearly 18 months, your UC score might show "zero income," which looks suspicious or risky to automated systems. During this "invisible" period, you are often forced to rely on prepaid services or use tools like Wise to manage your international funds and pay for things upfront while you wait for your Swedish financial identity to mature. Why You Need a Personnummer for Almost Every Financial Service in Sweden becomes painfully obvious when you realize that without that 12-digit number, UC can't even begin to track you.
How Your UC Score is Calculated: The Mechanics of Creditworthiness
The Swedish credit system is incredibly transparent but also rigid. It relies on a mathematical model that rewards stability and punishes "erratic" financial behavior. Understanding what goes into the blender to create your risk percentage is the first step toward controlling it.
Income and Tax Records: The Skatteverket Connection
Your declared income is the bedrock of your UC score. UC receives updates from Skatteverket once a year after the tax season. This is why Filing Your Swedish Tax Return (Deklaration): What You Need to Know is so vital; any errors or delays in your filing can directly impact your creditworthiness for the following year.
UC looks at your "Taxerad förvärvsinkomst" (taxable earned income). If your income jumps significantly from one year to the next, it’s seen as a positive, but they also look for consistency. If you are a freelancer or have a fluctuating income, the system might flag you as higher risk than a permanent employee with a lower but steady salary. For expats who have complex tax situations involving income from back home, using a service like Taxes for Expats can ensure your Swedish filings are accurate and don't accidentally under-report your global standing, though UC generally only cares about what is reported within Sweden.
Debt-to-Income Ratio and Existing Liabilities
UC knows about your other credits. If you have a car loan, a student loan from CSN, or even unused credit card limits, these are all factored in. A common mistake newcomers make is having multiple credit cards with high limits, even if the balance is zero. In the eyes of the UC algorithm, that is "potential debt" that you could rack up tomorrow.
When a bank calculates your ability to pay, they use a "KALP" (Kvar Att Leva På) calculation—literally "left to live on." They take your income, subtract taxes, housing costs, and your existing debt obligations. If your UC report shows you are heavily leveraged, your risk percentage will climb. If you are planning a major move, such as How Mortgages (Bolån) and the Amortisation Requirement Work in Sweden, cleaning up these small "lifestyle" debts is essential.
Credit Inquiries and Their Impact
Every time someone performs a "full" UC check on you, it is recorded as an "omfrågning" (inquiry). These stay on your record for 12 months. This is perhaps the most counter-intuitive part of the Swedish system for Americans or Brits. In many countries, "shopping around" for the best rate is encouraged. In Sweden, if you apply for five different loans in one month, UC sees five inquiries and assumes you are desperate for cash.
This can cause your score to plummet. If you are looking for a loan, it is better to use a loan broker (like Lendo or Sambla) who performs a single UC check but presents your application to multiple banks. This protects your score while still allowing you to compare rates.
The Impact of the Personnummer on Your Financial Identity
You will hear the word "Personnummer" more than your own name during your first year in Sweden. It is the master key to everything, and for UC, it is the unique identifier that ties your taxes, your debts, and your address together.
The Gateway to Swedish Healthcare and Finance
Without a Personnummer, you are essentially locked out of the standard credit system. While some banks might allow you to open a basic account with a "Samordningsnummer" (coordination number), UC rarely tracks these in the same way. You won't be able to get BankID, which is the digital signature required to check your own credit score on "Min UC."
If you are still in the waiting phase, Getting Your Personnummer: The Gateway to Swedish Healthcare is a must-read, as the timeline for your credit history starts the day you are entered into the population register. Every month you wait for that number is a month of "lost" credit history.
The "Wait and See" Period: Building History from Scratch
Once you have your Personnummer, the clock starts. However, a Personnummer with no history is often treated similarly to a bad credit score by automated systems. This is why many expats find that they can't even buy a vacuum cleaner on installments at Elgiganten during their first year.
The system needs to see that you have lived at the same address for a while (stability) and that you have at least one filed tax return. During this time, it is wise to keep your financial life simple. Avoid applying for unnecessary credits and use Wise for your currency exchanges and international transfers to keep your main Swedish bank account "clean" and focused on local utility payments and salary deposits.
Address Stability and the Population Register
UC also tracks how often you move. In the Swedish mindset, moving every six months is a sign of instability. If your "Folkbokföring" history shows three different addresses in two years, your risk prognos will likely be higher than someone who has stayed in the same apartment.
This is a particular challenge for expats stuck in the "second-hand" rental market, where contracts are often short-term. If you can, try to find a stable long-term sublet to show UC that you are settled. Understanding Renting a Home in Sweden: How the First- and Second-Hand System Works can help you strategize your moves to minimize the impact on your credit score.
Improving Your Credit Rating: Practical Strategies for Expats
If you’ve discovered that your UC score is less than stellar, don't panic. Unlike some systems that hold grudges for decades, the Swedish system is relatively quick to forgive—provided you change your habits.
Actionable Steps for a Better Score
The most effective way to lower your risk percentage is to reduce the number of credit inquiries. If you have ten inquiries from the last year, simply waiting for them to expire one by one will see your score improve significantly every month.
Another tip is to close unused credit accounts. If you have a store card from IKEA or a credit card from your bank that you don't use, call them and close the account entirely. Ensure they report the closure to UC. Having a high "available credit" to "income" ratio is a common reason for a "Fair" or "Poor" rating. For a deeper dive, check out our specific guide on How to Improve Your Credit Rating in Sweden.
Managing Your Betalningsanmärkningar
The "Betalningsanmärkning" (payment default) is the ultimate "no" in Swedish finance. This occurs if a debt goes unpaid, passes through a collection agency (Inkasso), and is finally reported to the Swedish Enforcement Authority (Kronofogden). Once you have a "prip" (as it's colloquially known), it stays on your UC for three years.
If you find yourself in this situation, the priority is to pay the debt immediately. While the mark stays, a "paid" status is infinitely better than an "active" debt. Read Dealing with Kronofogden: Debt Enforcement in Sweden to understand the legal process and how to prevent a simple forgotten bill from ruining your credit for years.
Comparison Table: Swedish Credit Information Agencies
While UC is the biggest, it isn't the only one. Depending on what you are applying for, a company might use Bisnode or Creditsafe instead. These often have slightly different criteria.
| Feature | UC (Upplysningscentralen) | Bisnode (Dun & Bradstreet) | Creditsafe |
|---|---|---|---|
| Primary Users | Big Banks, Mortgages, Major Landlords | Online Retailers, Klarna, Small Loans | Gyms, Mobile Providers, Subscriptions |
| Impact of Inquiries | High – Every check can lower your score | Lower – Inquiries are often hidden from other lenders | Minimal – Focuses more on current status than inquiries |
| Data Source | Skatteverket, Banks, Kronofogden | Skatteverket, Public Records | Skatteverket, Public Records |
| Visibility | You are notified by mail every time | You are notified by mail/digital mailbox | You are notified by mail/digital mailbox |
Renting, Borrowing, and Life Transitions
Your UC score is most critical during major life transitions. Whether you are moving from a sublet to your first "real" apartment or finally buying that cottage in Dalarna, your credit score will be the first thing the landlord or bank looks at.
Can a Bad UC Score Stop Me Renting?
In short: Yes. In the competitive Swedish housing market, landlords can afford to be picky. If there are 50 people in the queue for an apartment and you have a payment default or a high-risk UC score, you will likely be filtered out automatically.
However, private landlords are sometimes more flexible than "Bostadsbolag" (municipal housing companies). If your UC score is low because you are new, offering to show your employment contract or a larger deposit can sometimes bypass the automated rejection. We explore this further in Can a Bad UC Score Stop Me Renting an Apartment in Sweden?.
Getting Your First Credit Card
It's a bit of a Catch-22: you need credit to build a score, but you need a score to get credit. For a newcomer, getting a credit card from a traditional bank like SEB can be tough. They often want to see six months of salary history in that specific account first.
Don't go applying for every card you see on Instagram ads. Every rejection is an inquiry that hurts your score. Start with a "debit-style" credit card or a low-limit card from your primary bank after you've had a few salaries land. You can find more tips on this in Getting a Credit Card in Sweden as a Newcomer.
The Importance of the Digital Mailbox (Kivra)
In Sweden, you will get a letter every single time someone looks at your credit. This is called an "Omprövningskopia." If you don't have a digital mailbox like Kivra, your physical mailbox will be flooded with these. Kivra is essential for keeping track of your financial footprint and ensuring you don't miss a bill that could lead to a default.
Navigating the Mortgage Process
When you transition from renting to buying, the UC check becomes an interrogation. The bank won't just look at the score; they will look at every single line item. They will ask why you had a credit check from a car dealership three months ago or why your income was lower in 2022.
Prepare for this by pulling your own report from "Min UC" (a paid service) a few months before applying. This allows you to spot any errors—yes, they do happen—and fix them before a mortgage officer sees them. If you’re coming from a country with a different tax year, having your international records organized by Taxes for Expats can help explain any discrepancies in your reported wealth versus your Swedish taxable income.
Practical Resources and Final Thoughts
Navigating the UC system is about patience and precision. You cannot "hack" the system; you have to live through it. By keeping your inquiries low, your taxes accurate, and your address stable, you will eventually see that risk percentage drop into the "Utmärkt" (Excellent) category.
If you are just starting your journey, focus on the basics. Opening a Bank Account in Sweden: A Step-by-Step Guide and getting your Personnummer are your priorities. Everything else, including a perfect credit score, will follow in time. Use tools like Wise to bridge the gap in the meantime, and always, always pay your "faktura" on time. In Sweden, the postman often brings the most important financial news, so keep an eye on that mail slot.
Disclaimer
This article provides general information for educational purposes and does not constitute financial or legal advice. Credit scoring models and regulations in Sweden can change. Always consult with a qualified financial advisor or the relevant authorities regarding your specific financial situation.